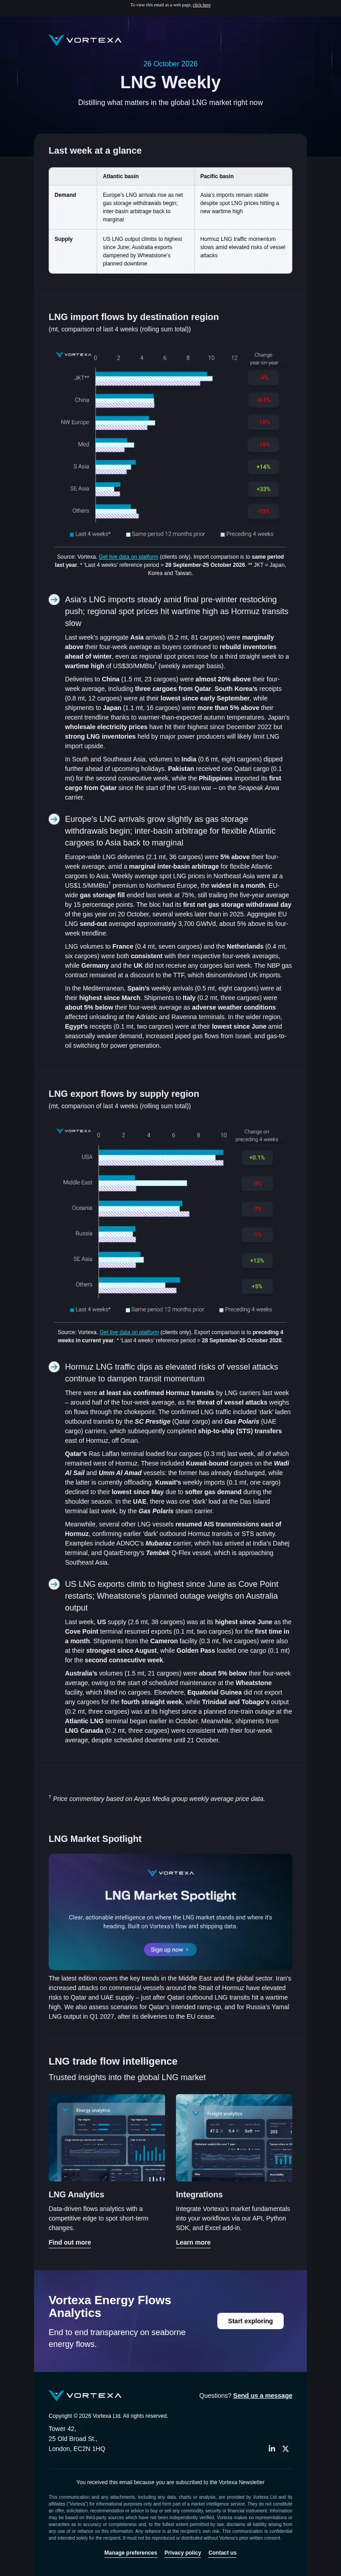
Vortexa LNG Weekly
Distilling what matters in the global LNG market right now.
- Product
- Vortexa
- Sent from
- vortexa.com
- Sent
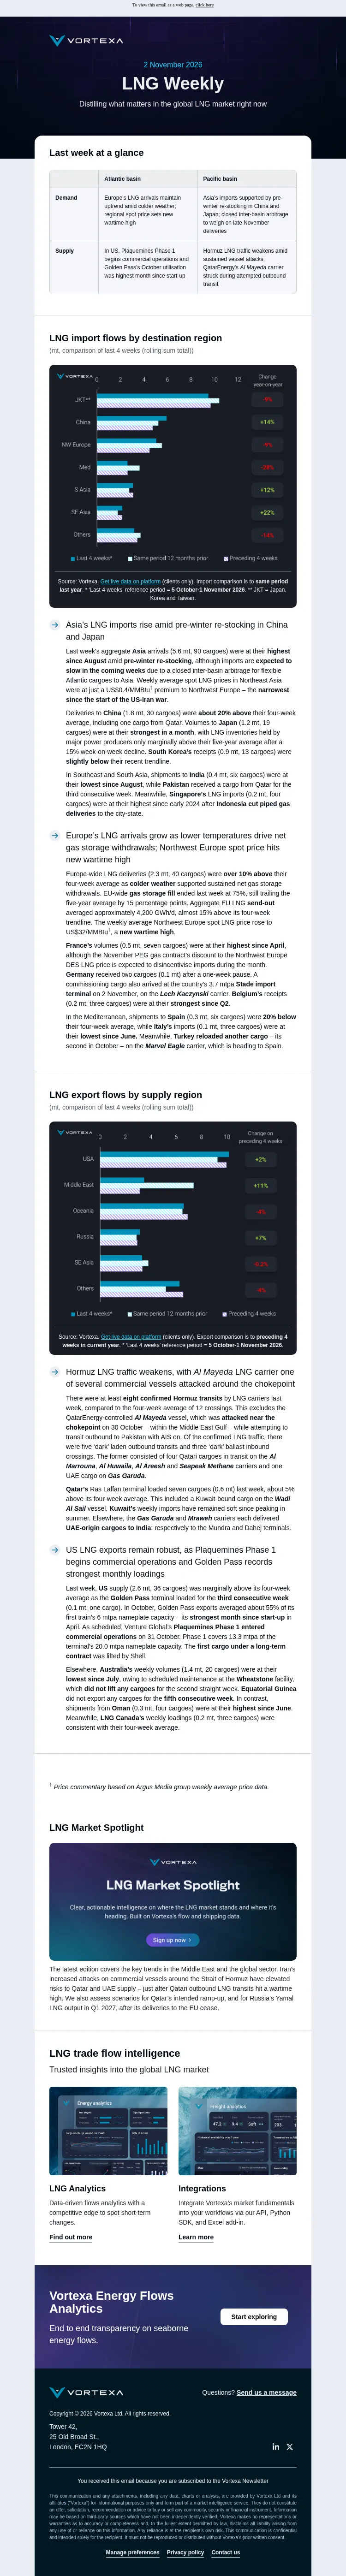
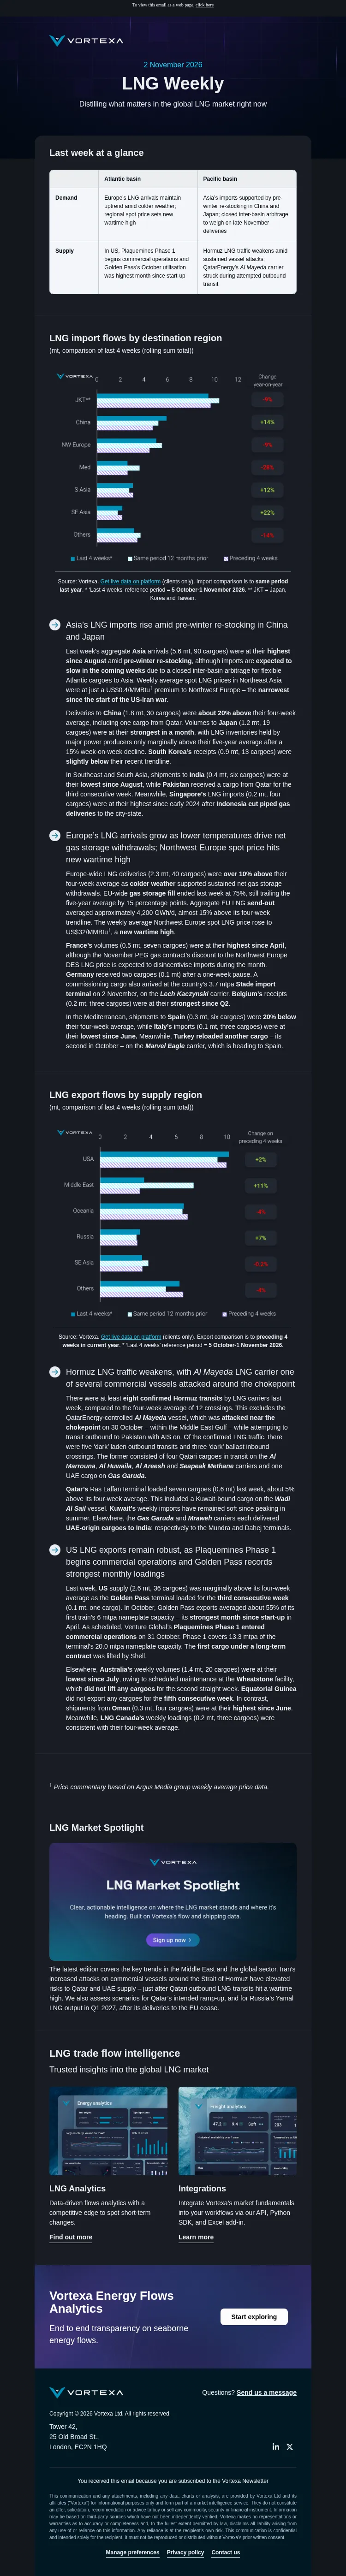
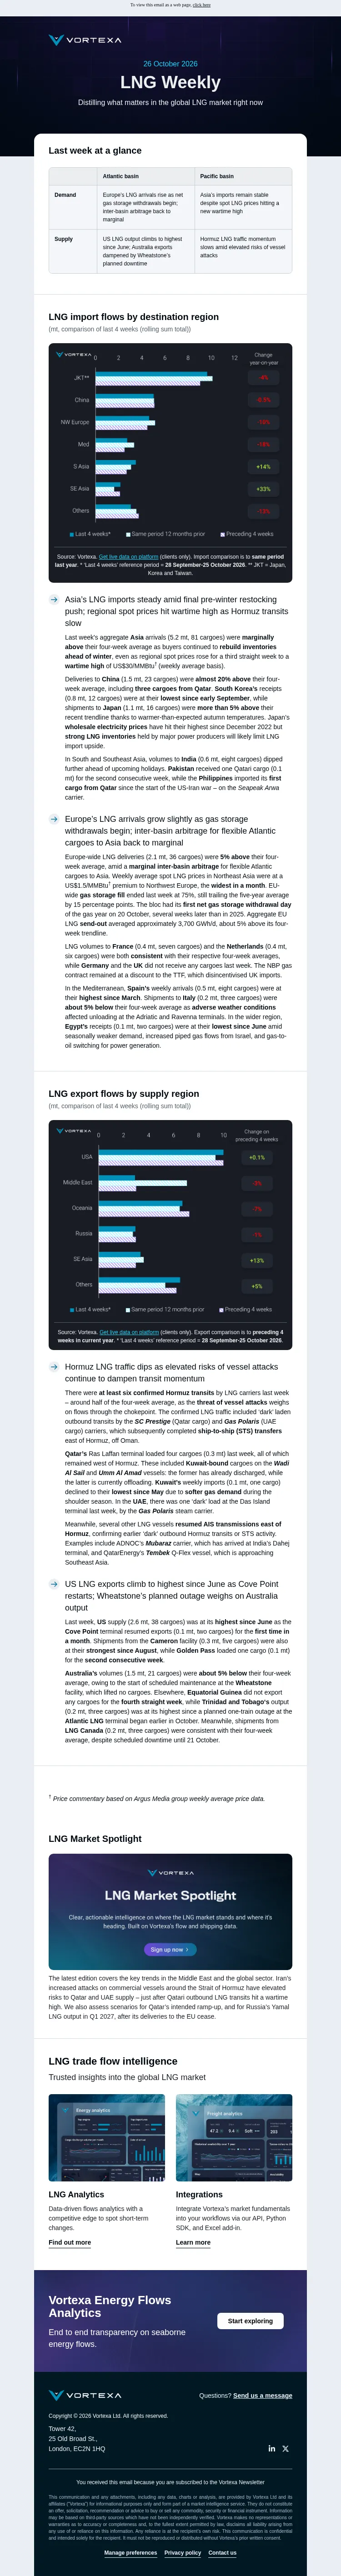
To view this email as a web page, go to the following address: https://marketinfo.vortexa.com/index.php/email/emailWebview?mkt_tok=ODM3LU1aRS01NzgAAAGlaVguEbA79aoc9d4l1X1w39W09lF4lszBjx0jmCvgi021Zj745_Q7HhR5USVxNNezOp02nASNDK2dZ567KH0yQPf1sH_heQlOLRTUftkMBVA ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguEfG29nKAAsvY1reFXY2YgBxM7MUPcFqjTEBvA1pxrSuAE2W9rwp3cuBrEEYMakPjDiw=) 11 November 2026LNG Weekly Distilling what matters in the global LNG market right nowIn partnership with KayrrosLast week at a glanceAtlantic basinPacific basinDemandEurope’s LNG arrivals stay firm as gas storage withdrawals pick up amid colder weatherAsia’s imports decline as elevated spot LNG prices weigh on demandSupplyUS LNG output stable as Golden Pass continues to ramp upHormuz LNG traffic maintains recent relative strength, led by outbound crossings by Qatari cargoes FOCUS TOPICLNG import flows by destination region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguESV1xhabAxa6blbP4kIh9O5gdET6WHpS5zVatIIc_QPOgTvJ3YcJra5LO1LXxRcr14U=) (clients only). Import comparison is to same period last year. * ‘Last 4 weeks’ reference period = 12 October-8 November 2026. ** JKT = Japan, Korea and Taiwan. Asia’s LNG imports fall as elevated spot LNG prices dampen demand Last week's aggregate Asia arrivals (4.3 mt, 66 cargoes) were at their lowest since September as elevated LNG prices weighed on demand. Average regional spot prices dipped 4% week-on-week to US$31/MMBtu†. Deliveries to China (1.2 mt, 18 cargoes) were almost 20% below their four-week average, including one cargo from Qatar. Volumes to Japan (0.8 mt, 13 cargoes) were at their weakest since September despite LNG inventories held by the country’s major power producers falling to 10% below their five-year average. South Korea’s receipts (0.8 mt, 12 cargoes) were 5% below their four-week average, partially supported by pre-winter re-stocking amid below-average LNG inventories. In Southeast and South Asia, shipments to India (0.5 mt, seven cargoes) were 5% below their four-week average. Pakistan and Singapore did not receive any cargoes last week, a first for the latter since July. In contrast, Thailand’s imports (0.4 mt, five cargoes) were at their highest since September, driven by stronger electricity demand and weaker coal-fired power generation. Europe’s LNG arrivals robust amid quicker gas storage withdrawals and closed inter-basin arbitrage Europe-wide LNG deliveries (2.2 mt, 36 cargoes) sustained the previous week’s strong level, amid an acceleration in winter gas storage withdrawals and a closed inter-basin arbitrage for flexible Atlantic supply to Asia. EU-wide gas storage fill ended last week at 72%, trailing the five-year average by 17 percentage points. Aggregate EU LNG send-out averaged approximately 4,000 GWh/d, 5% above its four-week trendline. Weekly average spot LNG prices in Northeast Asia have rebounded to a US$2.2/MMBtu† premium to Northwest Europe, the widest since September. The UK’s receipts (0.3 mt, four cargoes) were at their highest since March as a stronger November NBP gas contract relative to the TTF began to attract imports. France’s arrivals (0.3 mt, six cargoes) were about 15% below their four-week average, while shipments to Germany (0.2 mt, three cargoes) were at their strongest since Q3. In contrast, the Netherlands received four cargoes (0.3 mt), its weakest since September. In the Mediterranean, Spain’s imports (0.3 mt, six cargoes) were consistent with their four-week average, while Italy’s receipts (0.4 mt, six cargoes) were at their highest since August. The latter’s 2.8 mtpa Toscana terminal received its first post-maintenance cargo following a month-long planned outage. FOCUS TOPICLNG export flows by supply region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguEQ4V4eR5tSs0szyuhdLz9eOec6ykEOMNtSYddKWEJuhczYMBTzGxYz9bKeZJkyTz7pA=) (clients only). Export comparison is to preceding 4 weeks in current year. * ‘Last 4 weeks’ reference period = 12 October-8 November 2026. Hormuz LNG traffic maintains relative ongoing strength, led by outbound voyages by Qatari cargoes There were more than 15 confirmed Hormuz transits by LNG carriers last week, slightly above the four-week average. Of the confirmed LNG traffic, there were eight ‘dark’ laden outbound transits. These included six Qatari cargoes, of which one completed a ship-to-ship transfer (STS) east of Hormuz, off Oman. There were also two UAE cargoes on the Umm Al Ashtan and Tribhuwana carriers, with both signalling for arrival in India. Qatar’s Ras Laffan terminal loaded 10 cargoes (0.8 mt) last week, about 20% above its four-week average. This included one cargo discharged in Kuwait. Meanwhile, the UAE’s Das Island terminal loaded two cargoes (0.1 mt) last week. US LNG exports steady as Golden Pass ramps up; Australia’s output hits one-month high despite ongoing Wheatstone outage Last week, US supply (2.7 mt, 38 cargoes) was consistent with its four-week average as the Golden Pass terminal loaded one cargo (0.1 mt) for the fourth straight week. Elsewhere in the Atlantic basin, output from Trinidad and Tobago (0.2 mt, three cargoes) was at its highest since September, while Equatorial Guinea did not export any cargoes for the sixth consecutive week. In the Pacific basin, Australia’s volumes (1.5 mt, 22 cargoes) were at their strongest in a month, driven by increased exports from the Gorgon (0.4 mt, six cargoes) and North West Shelf (0.3 mt, four cargoes) terminals, which were each about 20% above their respective four-week averages. The Wheatstone facility did not load any cargoes for the third straight week due to scheduled downtime. † Price commentary based on Argus Media group weekly average price data.LNG Market SpotlightLNG Market Spotlight: sign up now (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguER0j_qMbgpC8a2UkxU9BnNudA7VP0WVeaImxlxd-XqnJUeLbZJ0BLXMMxR-KnbPU2hE=) The latest edition covers the key trends in the Middle East and the global sector. Iran’s increased attacks on commercial vessels around the Strait of Hormuz have elevated risks to Qatar and UAE supply – just after Qatari outbound LNG transits hit a wartime high. We also assess scenarios for Qatar’s intended ramp-up, and for Russia’s Yamal LNG output in Q1 2027, after its deliveries to the EU cease.LNG trade flow intelligence Trusted insights into the global LNG marketLNG intelligence dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguEZAzuqFLDbQg0X69KW6Hqjf90hqcFuGvFkkq1n509VzllGIey1ekQooFe82xgkq7x6g=) LNG Analytics Data-driven flows analytics with a competitive edge to spot short-term changes. Find out more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguEZAzuqFLDbQg0X69KW6Hqjf90hqcFuGvFkkq1n509VzllGIey1ekQooFe82xgkq7x6g=) Vortexa integrations (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguERPLEus_KzAymEl4yZdzBOP_HXvQdAL827uw9sF73n3cg3Ts3bQHgCXml58PwZqVdNE=) Integrations Integrate Vortexa’s market fundamentals into your workflows via our API, Python SDK, and Excel add-in. Learn more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguERPLEus_KzAymEl4yZdzBOP_HXvQdAL827uw9sF73n3cg3Ts3bQHgCXml58PwZqVdNE=) Vortexa Energy Flows Analytics End to end transparency on seaborne energy flows.Start exploring (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguEXBO35-OTHHsClB-f2lTkYRCiKQgIAQEUnoCo3JiX8rtP5YruJBOYJxYo1ekUYx5W3U=) Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguEfG29nKAAsvY1reFXY2YgBxM7MUPcFqjTEBvA1pxrSuAE2W9rwp3cuBrEEYMakPjDiw=) Questions? Send us a message (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguESvyLsKLzrKQ0rgDoytVa10E13KXIIKEp7UF3OtmQemxKTLl0YWkRpVRgkKdY1wjRtg=) Copyright © 2026 Vortexa Ltd. All rights reserved. Tower 42,25 Old Broad St.,London, EC2N 1HQLinkedIn (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguEebqzz9kV_JuDBjSgh0uAeCXt2PLYvxasYLy-y2DpciVz6pSm91ed9s0MwqRtAqUFxU=) X (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguESbFxNx9ItKOGGVVh6I_s3iV-3XToo1t47D4f2quPw3qMUuQTANcsv7TIF8pvAojHxM=) You received this email because you are subscribed to the Vortexa Newsletter This communication and any attachments, including any data, charts or analysis, are provided by Vortexa Ltd and its affiliates (“Vortexa”) for informational purposes only and form part of a market intelligence service. They do not constitute an offer, solicitation, recommendation or advice to buy or sell any commodity, security or financial instrument. Information may be based on third-party sources which have not been independently verified. Vortexa makes no representations or warranties as to accuracy or completeness and, to the fullest extent permitted by law, disclaims all liability arising from any use of or reliance on this information. Any reliance is at the recipient’s own risk. This communication is confidential and intended solely for the recipient. It must not be reproduced or distributed without Vortexa’s prior written consent. Manage preferences (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguEUPImHA4G_2qAT9IUaeOgAMbDv-gVVvsjdnNcNIekWx7ca_ydY-OHJtAoCpsUAGJFjo=) Privacy policy (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguEbsUrErX7UzC6J6vbc3E6IDs37lS-ulcF7ZiCw0H2WuDbj9PDvmhRcvwMfaera1rBuw=) Contact us (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlaVguESvyLsKLzrKQ0rgDoytVa10E13KXIIKEp7UF3OtmQemxKTLl0YWkRpVRgkKdY1wjRtg=) .
- Accession
- nse/vortexa/2026-11-11/6674
- From
- Vortexa · analysts@vortexa.com
- Sent
- 11 November 2026 · 11:00 UTC