Vortexa LNG Weekly
Distilling what matters in the global LNG market right now.
- Product
- Vortexa
- Sent from
- vortexa.com
- Sent
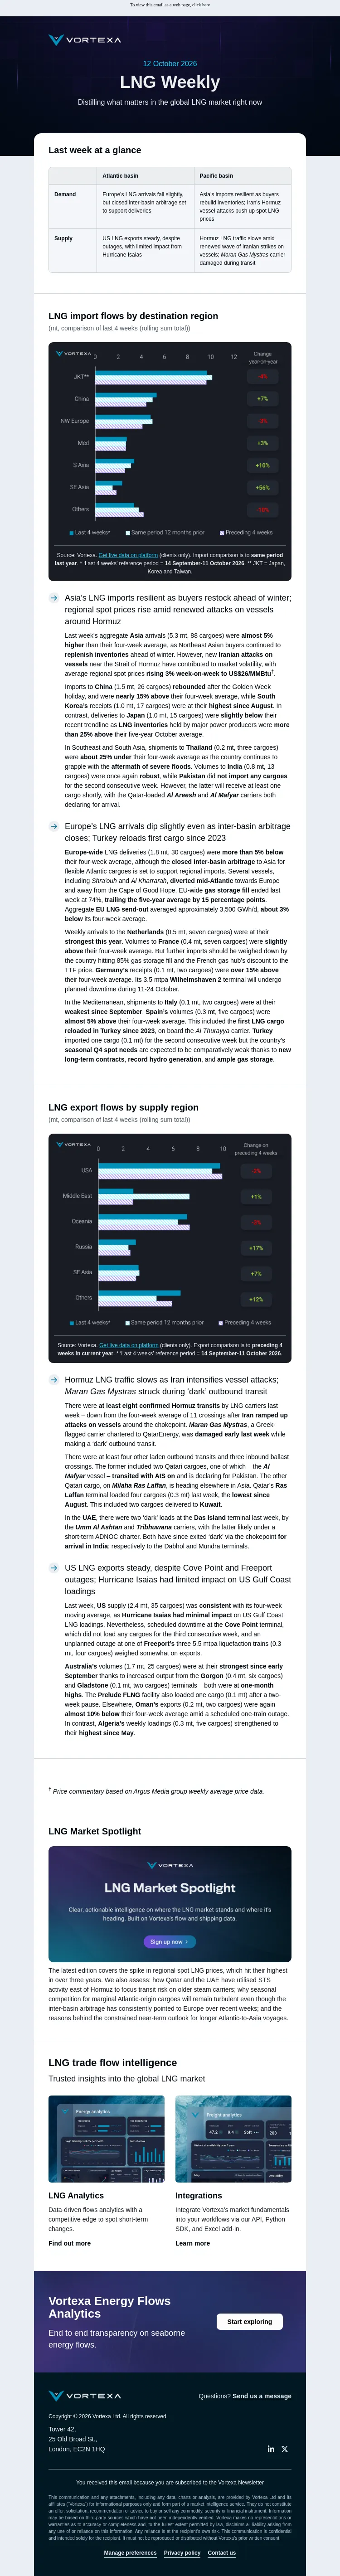
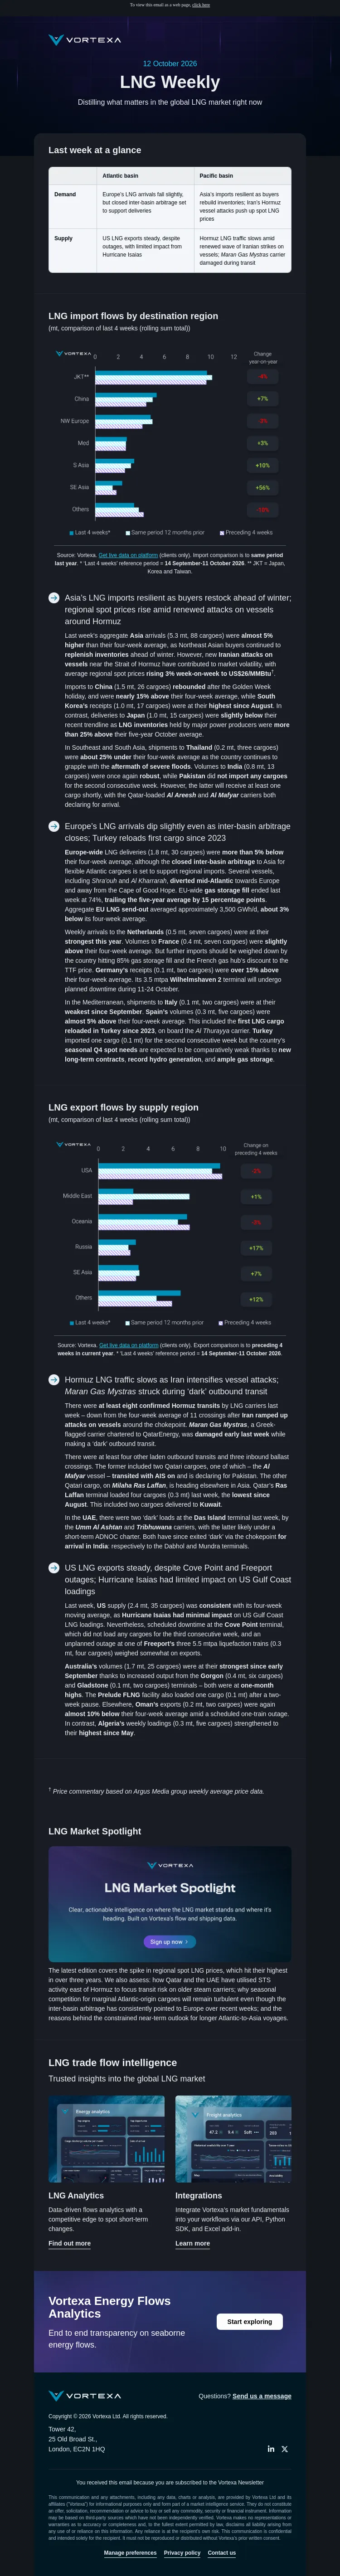
To view this email as a web page, go to the following address: https://marketinfo.vortexa.com/index.php/email/emailWebview?mkt_tok=ODM3LU1aRS01NzgAAAGk83ATOK5YmzU99mgpr1-l0nhcclzzcH3WBoU1svhFcALPWhrsskrY_t62zQMgK8OVHkWoOt3C1i5XH4PttAYqQJ8jMtrJfYqSxoduyIj9PiM ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATN62uDjwZbehOg7Myzsy4rZAq_QtdFQ_A2heZYcz2jq85Ed8wohUmu_AjYhbWuKq0LaU=) 19 October 2026LNG Weekly Distilling what matters in the global LNG market right nowIn partnership with KayrrosLast week at a glanceAtlantic basinPacific basinDemandEurope’s LNG arrivals boosted by lower hydro and nuclear power output; Northwest Europe spot LNG price at highest since late 2022Asia’s imports fall amid closed inter-basin arbitrage; Japan’s strong inventories weigh further on regional LNG demandSupplyUS LNG output shows continued strength; Algeria supply enjoys post-summer uptick, while Equatorial Guinea exports zero cargoes for third straight weekHormuz LNG traffic declines as Iran ramps up attacks on commercial shipping; Qatari cargo in transit to Poland via Red Sea – set for first new delivery to Europe since April FOCUS TOPICLNG import flows by destination region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOACb_2PkBXE775XU28ROGvrJFqm4chHV6hZ8YC9HfCVe4s7cFxeI50rvZG7FU8gS21k=) (clients only). Import comparison is to same period last year. * ‘Last 4 weeks’ reference period = 21 September-18 October 2026. ** JKT = Japan, Korea and Taiwan. Asia’s LNG imports dip amid Japan’s strong inventories and a closed inter-basin arbitrage for flexible Atlantic basin supply Last week's aggregate Asia arrivals (4.6 mt, 72 cargoes) were at their lowest in a month amid a closed inter-basin arbitrage for flexible Atlantic cargoes to Asia. Weekly average spot LNG prices in Northeast Asia were at a US$0.8/MMBtu† premium to Northwest Europe, narrowing by 20% week-on-week. Imports to China (1.2 mt, 19 cargoes) were in line with their four-week average, including one Qatari cargo on the Al Shamal carrier. Deliveries to South Korea (0.9 mt, 13 cargoes) and Japan (0.9 mt, 13 cargoes) were each at their lowest since late September. Japan’s LNG demand has been weighed down by milder temperatures during the shoulder months and strong LNG inventories at its major power producers, which were at their highest since end-2023. In South Asia, India’s receipts (0.6 mt, nine cargoes) were almost 15% below their four-week average. In contrast, shipments to Bangladesh (0.2 mt, three cargoes) were more than 10% above the same metric, including its first Qatari cargo since July on the Milaha Ras Laffan carrier. Pakistan also received one Qatari cargo (0.1 mt) last week, on the Al Areesh vessel after its ‘dark’ Hormuz transit earlier in October. Europe’s LNG arrivals supported by lower hydro and nuclear output, as regional spot price climbs to four-year high; Qatari cargo in transit to Poland via Red Sea – will be Europe’s first delivery from west of Hormuz since April Europe-wide LNG deliveries (2.0 mt, 35 cargoes) were slightly below their four-week average, albeit bolstered by weaker hydro and nuclear power availability caused by low river water levels. The weekly average Northwest Europe spot LNG price rose to US$27.8/MMBtu†, its highest since late 2022. EU-wide gas storage fill ended last week at 74%, still trailing the five-year average by 15 percentage points. Aggregate EU LNG send-out averaged approximately 3,600 GWh/d, consistent with its four-week average. France’s receipts (0.4 mt, seven cargoes) were on par with their four-week average. The UK received three cargoes (0.1 mt), even as the steep contango between the front-month and November NBP contract incentivises importers to delay shipments. Deliveries to Belgium (0.1 mt, three cargoes) and Poland (0.1 mt, one cargo) each resumed after a one-week pause. In the Mediterranean, Italy’s imports (0.2 mt, four cargoes) were about 5% below their four-week average amid planned maintenance at the 2.8 mtpa Toscana terminal (from 8 October to 4 November). Arrivals to Spain (0.3 mt, four cargoes) were at their weakest since September. Notably, Europe is set to receive its first Qatari LNG cargo since April, with QatarEnergy’s Al Kharsaah carrier declaring for arrival in Poland in mid-November. The vessel is currently making a very rare LNG transit of the Bab-el-Mandeb / Red Sea route – despite the shipping risks – and came under attack in the Gulf of Aden. FOCUS TOPICLNG export flows by supply region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOGHrmqtG1xOt0xGKPYELCQFo2hSOHjojKeMtkPNJG5ho9HDlRYdnMrGKRQj95l0pj90=) (clients only). Export comparison is to preceding 4 weeks in current year. * ‘Last 4 weeks’ reference period = 21 September-18 October 2026. Hormuz LNG traffic declines as risks heighten from increased attacks on commercial shipping There were at least five confirmed Hormuz transits by LNG carriers last week, a sharp drop from the four-week average of 12 crossings as attacks on commercial ships continued to escalate around the chokepoint. Of the confirmed LNG traffic, there were two laden outbound transits and three ballast inbound crossings. The former consisted of two Qatari cargoes in transit on Cool Rover and Al Sheehaniya, with both exiting Hormuz ‘dark’ before resuming AIS transmissions in the Indian Ocean. Qatar’s Ras Laffan terminal loaded five cargoes (0.4 mt) last week. These included the Tembek and SC Prestige carriers, which made two of the ballast inbound crossings. Meanwhile, two other Qatari cargoes – Wadi Al Sail and Qtaifan – unloaded in Kuwait. In the UAE, there was one ‘dark’ load at the Das Island terminal last week, by the Gas Garuda steam carrier following its latest ‘dark’ inbound transit. Elsewhere, the Tribhuwana and Umm Al Ashtan vessels each delivered a UAE-origin cargo to India: respectively to the Mundra and Dabhol terminals. US LNG exports show continued strength, while Algeria supply enjoys post-summer uptick; LNG Canada’s scheduled outage had limited impact on loadings Last week, US supply (2.5 mt, 36 cargoes) was about 5% above its four-week average, boosted by stronger output from the Freeport and Sabine Pass facilities. The Golden Pass terminal also loaded its latest cargo – its eleventh to date. So far in October, Golden Pass exports have averaged about 50% of its first train’s 6 mtpa nameplate capacity. No cargoes loaded at the Cove Point terminal, although feedgas flows did rebound to normal levels on 12 October after planned maintenance completed. Exports are expected to resume shortly. Australia’s volumes (1.5 mt, 22 cargoes) were marginally under their four-week average, with no cargoes lifted from the Darwin and Prelude facilities. Elsewhere, Equatorial Guinea did not export any cargoes for the third consecutive week. In contrast, shipments from Algeria (0.3 mt, six cargoes) were at their strongest since Q2, with loadings having recovered from their summer slowdown. Oman’s output (0.2 mt, three cargoes) was also at its highest since a scheduled one-train outage began in early September. Meanwhile, LNG Canada’s weekly loadings (0.2 mt, three cargoes) were consistent with their four-week average despite planned downtime across 12-21 October. † Price commentary based on Argus Media group weekly average price data. FOCUS TOPICLNG Market SpotlightFocus topic chart (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOGaswwjAj3nt8gzi4bPIKSzV9IGtF9etBUgQYYYzbBh3S9cwXnss7RDINgIo3H7WgKI=) Source: Vortexa, KayrosDaily data from the last 3 months - updated for 26 January 2026 The latest edition covers the key trends in the Middle East and the global sector. Iran’s increased attacks on commercial vessels around the Strait of Hormuz have elevated risks to Qatar and UAE supply – just after Qatari outbound LNG transits hit a wartime high. We also assess scenarios for Qatar’s intended ramp-up, and for Russia’s Yamal LNG output in Q1 2027, after its deliveries to the EU cease.LNG trade flow intelligence Trusted insights into the global LNG marketLNG intelligence dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOFP3ownC-vSwwCW0QHKLM6FmRG2dva20E4k_ttiMMl2IY0yxP8TUJrCC00RHN_q7_60=) LNG Analytics Data-driven flows analytics with a competitive edge to spot short-term changes. Find out more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOFP3ownC-vSwwCW0QHKLM6FmRG2dva20E4k_ttiMMl2IY0yxP8TUJrCC00RHN_q7_60=) Outage report dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOAley1ACWRXRbQeqUieuGQpAdKIKZTvbdWJ4pHOwUfN5aeLB7Sdlidy9YRyZacNwyug=) Integrations Integrate Vortexa’s market fundamentals into your workflows via our API, Python SDK, and Excel add-in. Learn more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOAley1ACWRXRbQeqUieuGQpAdKIKZTvbdWJ4pHOwUfN5aeLB7Sdlidy9YRyZacNwyug=) Vortexa Energy Flows Analytics End to end transparency on seaborne energy flows.Start exploring (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOOUjiTP5j_KBQQoGP2gKwNcVfqG3j90xQvIJIk6u9K1ozPT4DyaTvJYNhlWUG5u1iCw=) Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATN62uDjwZbehOg7Myzsy4rZAq_QtdFQ_A2heZYcz2jq85Ed8wohUmu_AjYhbWuKq0LaU=) Questions? Send us a message (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOBmLPGpesBHLQBLwzgtdB1WF5e05b1aMjIZ2ZtxIWBAIjJ7tvvih9AdhBAXncZFxFHE=) Copyright © 2026 Vortexa Ltd. All rights reserved. Tower 42,25 Old Broad St.,London, EC2N 1HQLinkedIn (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOMj1Vv19_p6hr7vCvBSdmtq1bFs0owJcP97uwBDGwWX0wpO59AUc249oztaH0ipTFew=) X (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOOxtX9XqRa1bRdZz0ysjCm1Dk_692cEsx_0VCyQw95JNhayhLSQQod8ImqTvklbDBcU=) You received this email because you are subscribed to the Vortexa Newsletter This communication and any attachments, including any data, charts or analysis, are provided by Vortexa Ltd and its affiliates (“Vortexa”) for informational purposes only and form part of a market intelligence service. They do not constitute an offer, solicitation, recommendation or advice to buy or sell any commodity, security or financial instrument. Information may be based on third-party sources which have not been independently verified. Vortexa makes no representations or warranties as to accuracy or completeness and, to the fullest extent permitted by law, disclaims all liability arising from any use of or reliance on this information. Any reliance is at the recipient’s own risk. This communication is confidential and intended solely for the recipient. It must not be reproduced or distributed without Vortexa’s prior written consent. Manage preferences (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATN1JLkzM9UfUtdWazGTSoM0qaY-HVTD1a2XCsQMKlhuRDfkVvJ2wPcr4xgZA0p4KWidY=) Privacy policy (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOFse6l_pdK3xqDi0KIvJugHYxxwaGAT8HB5iyrER3Ko9qz0VR6PxdTK1vLbz6aTdQnk=) Contact us (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGk83ATOBmLPGpesBHLQBLwzgtdB1WF5e05b1aMjIZ2ZtxIWBAIjJ7tvvih9AdhBAXncZFxFHE=) .
- Accession
- nse/vortexa/2026-10-19/4388
- From
- Vortexa · analysts@vortexa.com
- Sent
- 19 October 2026 · 14:00 UTC