Vortexa LNG Weekly
Distilling what matters in the global LNG market right now.
- Product
- Vortexa
- Sent from
- vortexa.com
- Sent
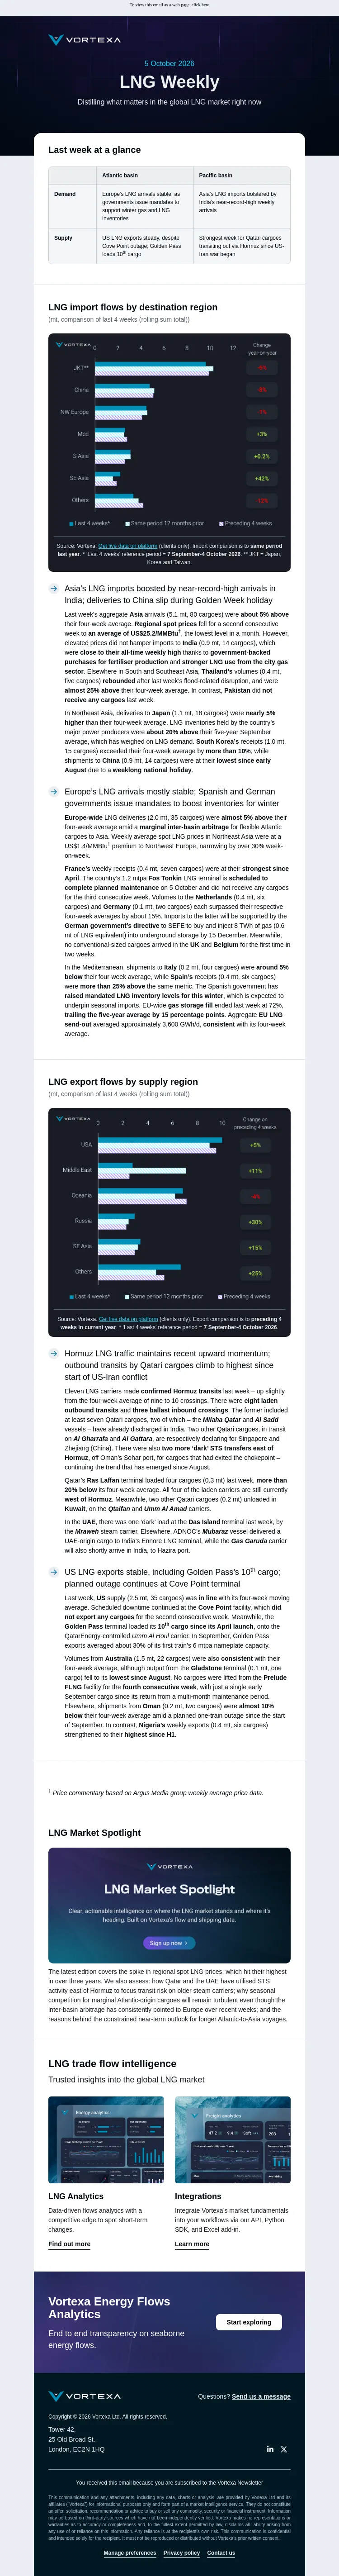
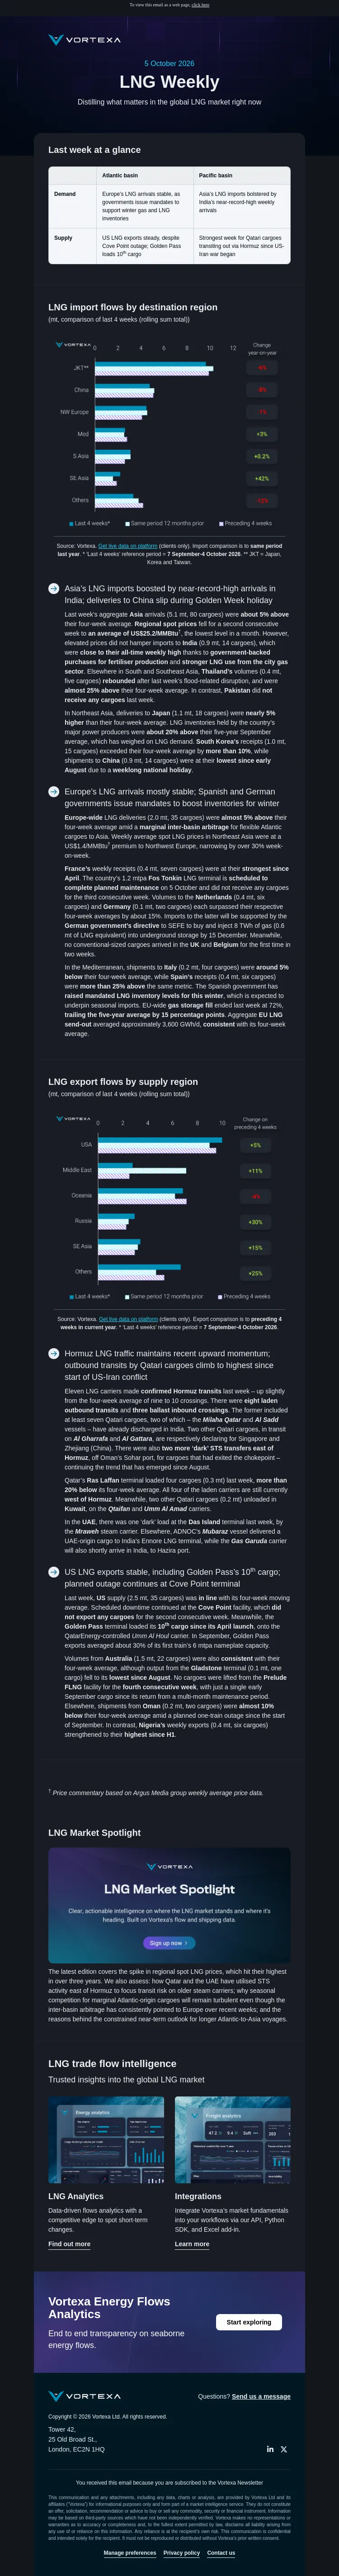
To view this email as a web page, go to the following address: https://marketinfo.vortexa.com/index.php/email/emailWebview?mkt_tok=ODM3LU1aRS01NzgAAAGkz9CJfUAsDTFnc15BfMNLdu053IWJZOCFkdaDd9v-_hduGwLNoRU-1NGTHwWtrKPRMkovWojg0QRvI8iWTqGiW-8C8UczVQdJHl6hUAHGmoI ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfPnLzooPRKbxtwTQRJrG70o9fJeyiOHk3KZJEiqM-EN-qtjy2-PMbkkH3q78zfwYS9A=) 12 October 2026LNG Weekly Distilling what matters in the global LNG market right nowIn partnership with KayrrosLast week at a glanceAtlantic basinPacific basinDemandEurope’s LNG arrivals fall slightly, but closed inter-basin arbitrage set to support deliveriesAsia’s imports resilient as buyers rebuild inventories; Iran’s Hormuz vessel attacks push up spot LNG pricesSupplyUS LNG exports steady, despite outages, with limited impact from Hurricane IsaiasHormuz LNG traffic slows amid renewed wave of Iranian strikes on vessels; Maran Gas Mystras carrier damaged during transit FOCUS TOPICLNG import flows by destination region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfFC0mxDTnvCvr9FgsiTKtSWsAyVybJ_Le1IW1mqAXlE-LQPR3ITTOYH-8SgxC2xGMVw=) (clients only). Import comparison is to same period last year. * ‘Last 4 weeks’ reference period = 14 September-11 October 2026. ** JKT = Japan, Korea and Taiwan. Asia’s LNG imports resilient as buyers restock ahead of winter; regional spot prices rise amid renewed attacks on vessels around Hormuz Last week's aggregate Asia arrivals (5.3 mt, 88 cargoes) were almost 5% higher than their four-week average, as Northeast Asian buyers continued to replenish inventories ahead of winter. However, new Iranian attacks on vessels near the Strait of Hormuz have contributed to market volatility, with average regional spot prices rising 3% week-on-week to US$26/MMBtu†. Imports to China (1.5 mt, 26 cargoes) rebounded after the Golden Week holiday, and were nearly 15% above their four-week average, while South Korea’s receipts (1.0 mt, 17 cargoes) were at their highest since August. In contrast, deliveries to Japan (1.0 mt, 15 cargoes) were slightly below their recent trendline as LNG inventories held by major power producers were more than 25% above their five-year October average. In Southeast and South Asia, shipments to Thailand (0.2 mt, three cargoes) were about 25% under their four-week average as the country continues to grapple with the aftermath of severe floods. Volumes to India (0.8 mt, 13 cargoes) were once again robust, while Pakistan did not import any cargoes for the second consecutive week. However, the latter will receive at least one cargo shortly, with the Qatar-loaded Al Areesh and Al Mafyar carriers both declaring for arrival. Europe’s LNG arrivals dip slightly even as inter-basin arbitrage closes; Turkey reloads first cargo since 2023 Europe-wide LNG deliveries (1.8 mt, 30 cargoes) were more than 5% below their four-week average, although the closed inter-basin arbitrage to Asia for flexible Atlantic cargoes is set to support regional imports. Several vessels, including Shra'ouh and Al Kharrarah, diverted mid-Atlantic towards Europe and away from the Cape of Good Hope. EU-wide gas storage fill ended last week at 74%, trailing the five-year average by 15 percentage points. Aggregate EU LNG send-out averaged approximately 3,500 GWh/d, about 3% below its four-week average. Weekly arrivals to the Netherlands (0.5 mt, seven cargoes) were at their strongest this year. Volumes to France (0.4 mt, seven cargoes) were slightly above their four-week average. But further imports should be weighed down by the country hitting 85% gas storage fill and the French gas hub’s discount to the TTF price. Germany’s receipts (0.1 mt, two cargoes) were over 15% above their four-week average. Its 3.5 mtpa Wilhelmshaven 2 terminal will undergo planned downtime during 11-24 October. In the Mediterranean, shipments to Italy (0.1 mt, two cargoes) were at their weakest since September. Spain’s volumes (0.3 mt, five cargoes) were almost 5% above their four-week average. This included the first LNG cargo reloaded in Turkey since 2023, on board the Al Thurayya carrier. Turkey imported one cargo (0.1 mt) for the second consecutive week but the country’s seasonal Q4 spot needs are expected to be comparatively weak thanks to new long-term contracts, record hydro generation, and ample gas storage. FOCUS TOPICLNG export flows by supply region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfKEGCL_k1TtSNgN6h70t5O2ZIJWXm5S3BbszYyIfyaWdufi6BCfJOKjrOJVd4vEXGsE=) (clients only). Export comparison is to preceding 4 weeks in current year. * ‘Last 4 weeks’ reference period = 14 September-11 October 2026. Hormuz LNG traffic slows as Iran intensifies vessel attacks; Maran Gas Mystras struck during ‘dark’ outbound transit There were at least eight confirmed Hormuz transits by LNG carriers last week – down from the four-week average of 11 crossings after Iran ramped up attacks on vessels around the chokepoint. Maran Gas Mystras, a Greek-flagged carrier chartered to QatarEnergy, was damaged early last week while making a ‘dark’ outbound transit. There were at least four other laden outbound transits and three inbound ballast crossings. The former included two Qatari cargoes, one of which – the Al Mafyar vessel – transited with AIS on and is declaring for Pakistan. The other Qatari cargo, on Milaha Ras Laffan, is heading elsewhere in Asia. Qatar’s Ras Laffan terminal loaded four cargoes (0.3 mt) last week, the lowest since August. This included two cargoes delivered to Kuwait. In the UAE, there were two ‘dark’ loads at the Das Island terminal last week, by the Umm Al Ashtan and Tribhuwana carriers, with the latter likely under a short-term ADNOC charter. Both have since exited ‘dark’ via the chokepoint for arrival in India: respectively to the Dabhol and Mundra terminals. US LNG exports steady, despite Cove Point and Freeport outages; Hurricane Isaias had limited impact on US Gulf Coast loadings Last week, US supply (2.4 mt, 35 cargoes) was consistent with its four-week moving average, as Hurricane Isaias had minimal impact on US Gulf Coast LNG loadings. Nevertheless, scheduled downtime at the Cove Point terminal, which did not load any cargoes for the third consecutive week, and an unplanned outage at one of Freeport’s three 5.5 mtpa liquefaction trains (0.3 mt, four cargoes) weighed somewhat on exports. Australia’s volumes (1.7 mt, 25 cargoes) were at their strongest since early September thanks to increased output from the Gorgon (0.4 mt, six cargoes) and Gladstone (0.1 mt, two cargoes) terminals – both were at one-month highs. The Prelude FLNG facility also loaded one cargo (0.1 mt) after a two-week pause. Elsewhere, Oman’s exports (0.2 mt, two cargoes) were again almost 10% below their four-week average amid a scheduled one-train outage. In contrast, Algeria’s weekly loadings (0.3 mt, five cargoes) strengthened to their highest since May. † Price commentary based on Argus Media group weekly average price data. FOCUS TOPICLNG Market SpotlightFocus topic chart (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfAzZF-TuMdcNip4Kh1HeWvSzIM4EjF3S55suENGDiO8IKP2nNaNmOKL9rLluJNfa3Yk=) Source: Vortexa, KayrosDaily data from the last 3 months - updated for 26 January 2026 The latest edition covers the spike in regional spot LNG prices, which hit their highest in over three years. We also assess: how Qatar and the UAE have utilised STS activity east of Hormuz to focus transit risk on older steam carriers; why seasonal competition for marginal Atlantic-origin cargoes will remain turbulent even though the inter-basin arbitrage has consistently pointed to Europe over recent weeks; and the reasons behind the constrained near-term outlook for longer Atlantic-to-Asia voyages.LNG trade flow intelligence Trusted insights into the global LNG marketLNG intelligence dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfDFJs9sO2fQqisQFtsfTsOI7254C-GBDHXPZEonVQ2sUa1VoUPeuXVy2hgdFDnQPVQo=) LNG Analytics Data-driven flows analytics with a competitive edge to spot short-term changes. Find out more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfDFJs9sO2fQqisQFtsfTsOI7254C-GBDHXPZEonVQ2sUa1VoUPeuXVy2hgdFDnQPVQo=) Outage report dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfMmpno2ght8kBar0zwFCtQ-mMUpyHeLOhdi-g-a-lKFnPADeKEtXh-0PyiXTTXYr_bk=) Integrations Integrate Vortexa’s market fundamentals into your workflows via our API, Python SDK, and Excel add-in. Learn more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfMmpno2ght8kBar0zwFCtQ-mMUpyHeLOhdi-g-a-lKFnPADeKEtXh-0PyiXTTXYr_bk=) Vortexa Energy Flows Analytics End to end transparency on seaborne energy flows.Start exploring (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfC5rIqDtPADJpy5kFuOl9qLAQewqoN3wIne9Bv_9D2sGjD6y8YDVosqjDZ9h0x6KIXY=) Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfPnLzooPRKbxtwTQRJrG70o9fJeyiOHk3KZJEiqM-EN-qtjy2-PMbkkH3q78zfwYS9A=) Questions? Send us a message (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfAw4wvm8MfDU91RDd1-jd1Mvz7Q4SBiPWe1gJvRqstXwW4_PDm_HhBNAaV08XFn1SgU=) Copyright © 2026 Vortexa Ltd. All rights reserved. Tower 42,25 Old Broad St.,London, EC2N 1HQLinkedIn (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfJ-3Gm07Afg8HPLzIguu8-1V5L4lln1eNkp__PJiKqaOTa7V_s9jNBvWdg9hfYXLXL8=) X (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfHFyIjl7BXKA3fX1qX3PM1VxbiJlZQrmSnN4vYXLMvN6cc26Ygr6siFlzfltgWQfBS0=) You received this email because you are subscribed to the Vortexa Newsletter This communication and any attachments, including any data, charts or analysis, are provided by Vortexa Ltd and its affiliates (“Vortexa”) for informational purposes only and form part of a market intelligence service. They do not constitute an offer, solicitation, recommendation or advice to buy or sell any commodity, security or financial instrument. Information may be based on third-party sources which have not been independently verified. Vortexa makes no representations or warranties as to accuracy or completeness and, to the fullest extent permitted by law, disclaims all liability arising from any use of or reliance on this information. Any reliance is at the recipient’s own risk. This communication is confidential and intended solely for the recipient. It must not be reproduced or distributed without Vortexa’s prior written consent. Manage preferences (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfGBvbhKdvyFVhux9Jq_3nIx1h-JfpX4CjHPNZ7WK70GmNMFNFrQyPh3Q9SZo17PjkIU=) Privacy policy (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfKDQeINnLfYAZCGOOc-Fvb46J4wZqcDQyOuH_DhgSlxE35L_0IQesxtOBWBmCwDGSAY=) Contact us (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkz9CJfAw4wvm8MfDU91RDd1-jd1Mvz7Q4SBiPWe1gJvRqstXwW4_PDm_HhBNAaV08XFn1SgU=) .
- Accession
- nse/vortexa/2026-10-12/3954
- From
- Vortexa · analysts@vortexa.com
- Sent
- 12 October 2026 · 16:00 UTC