Vortexa LNG Weekly
Distilling what matters in the global LNG market right now.
- Product
- Vortexa
- Sent from
- vortexa.com
- Sent
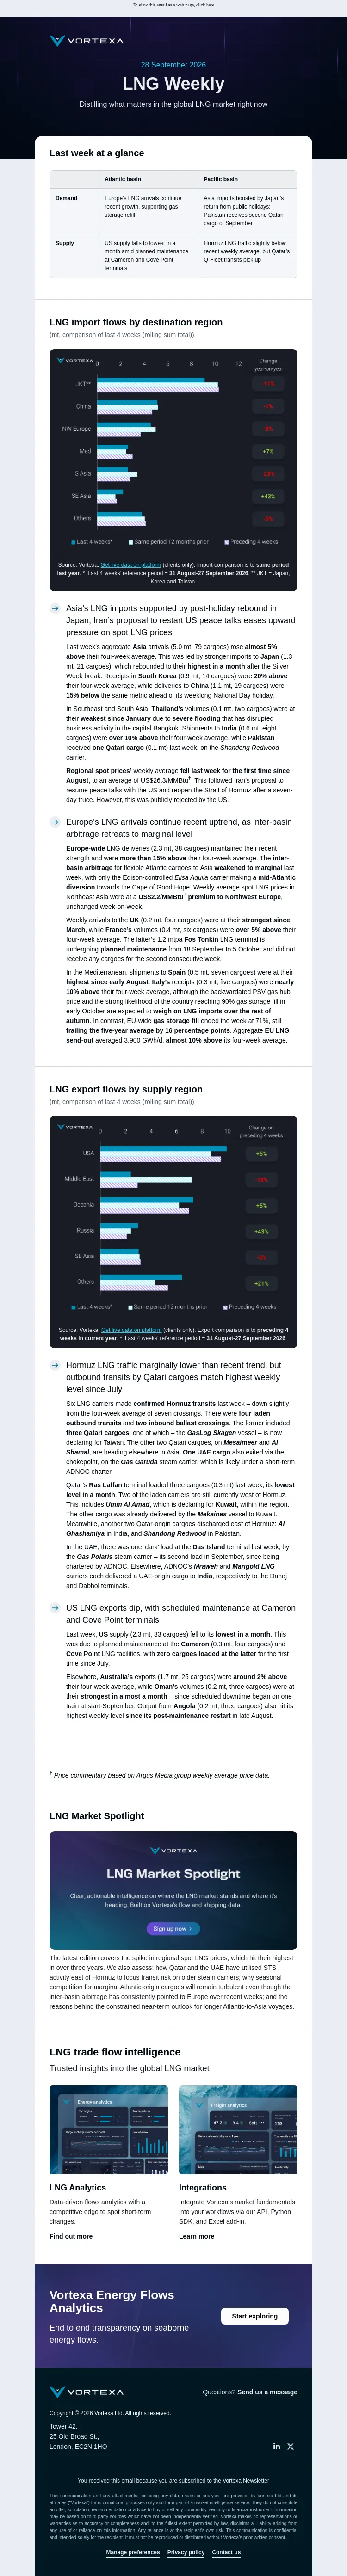
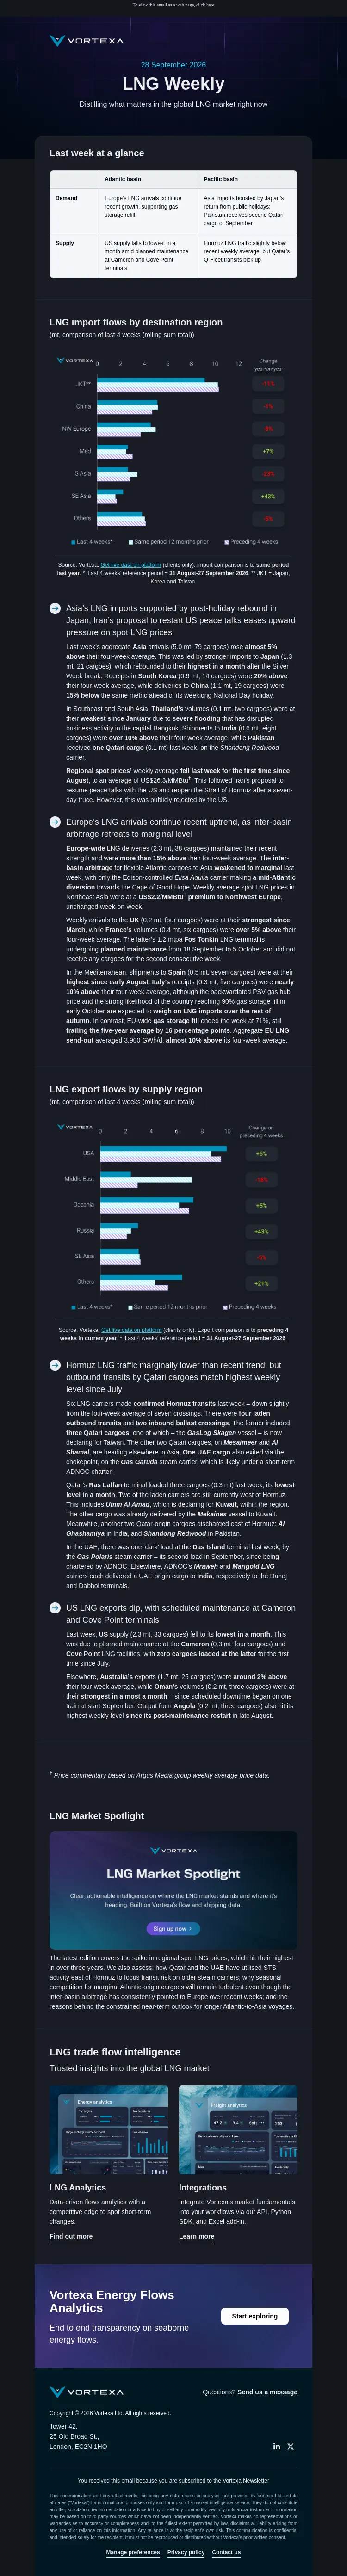
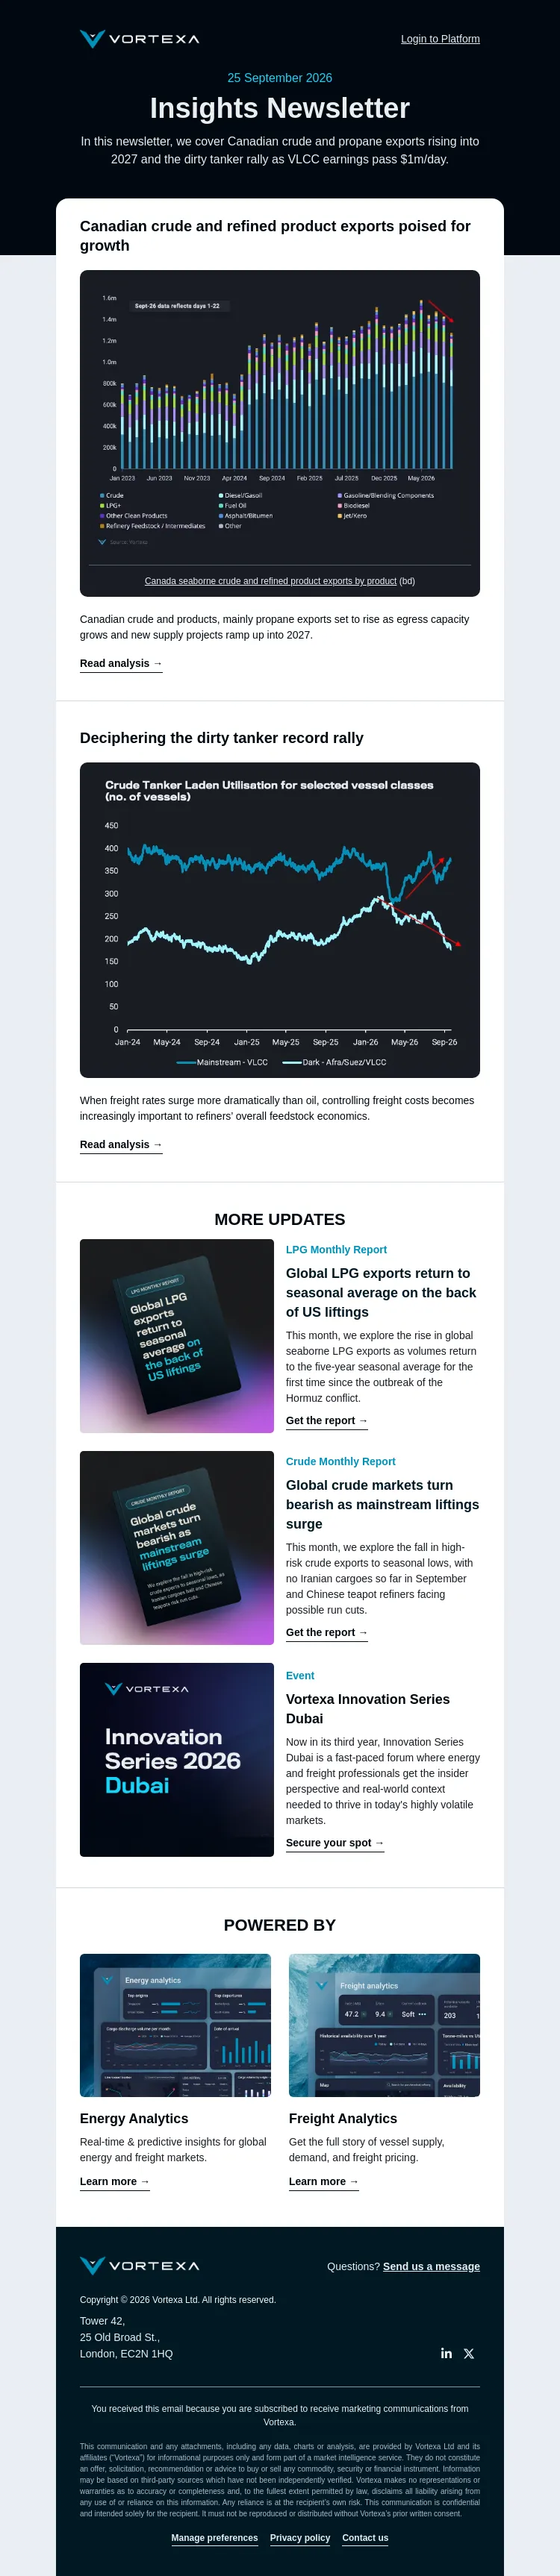
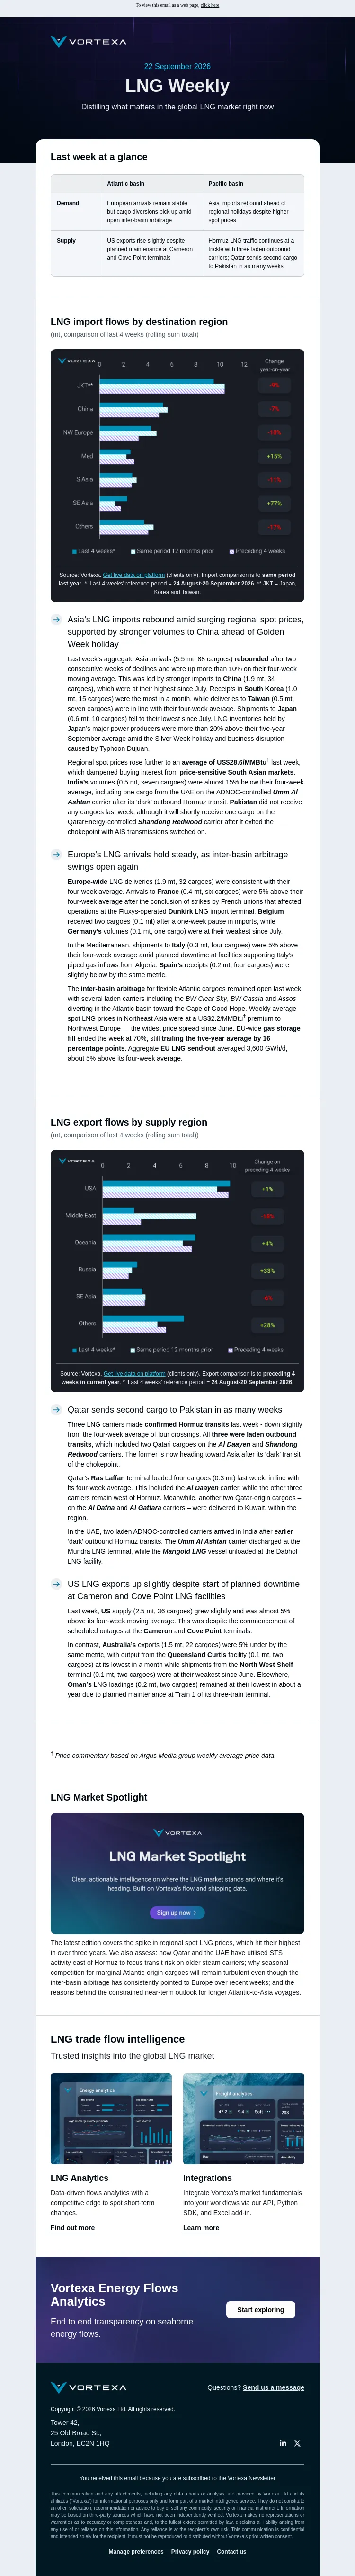
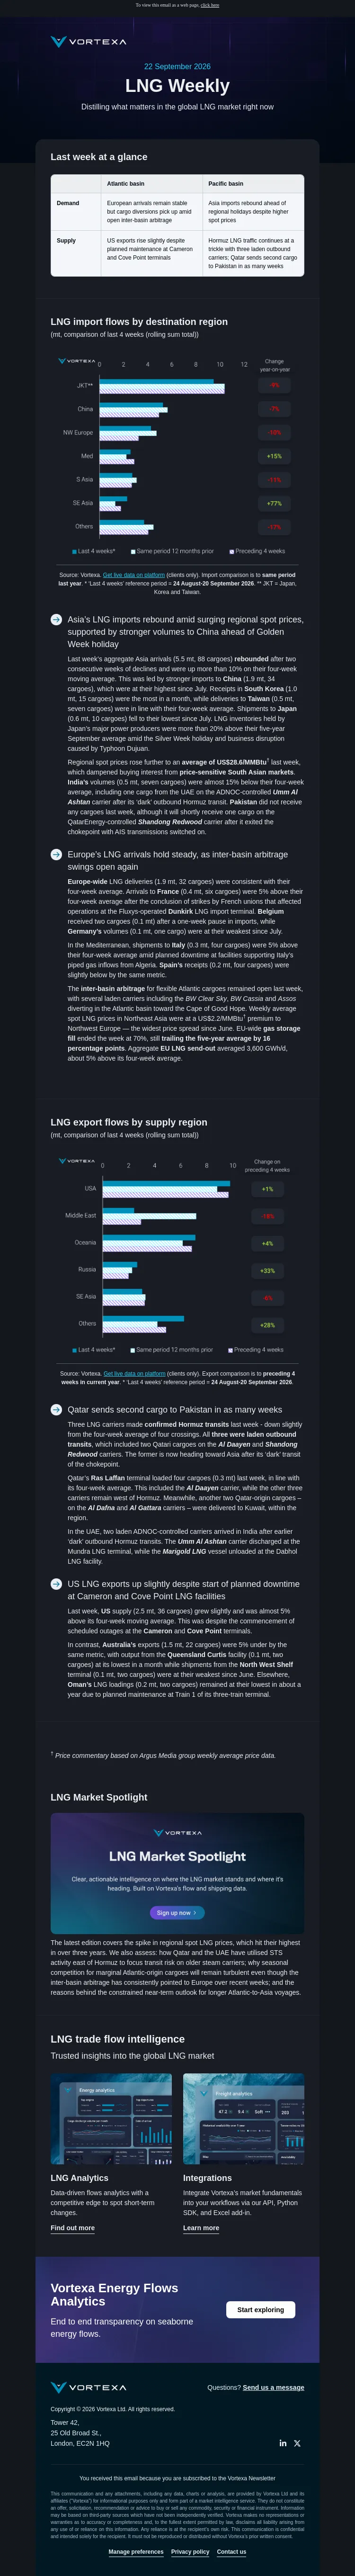
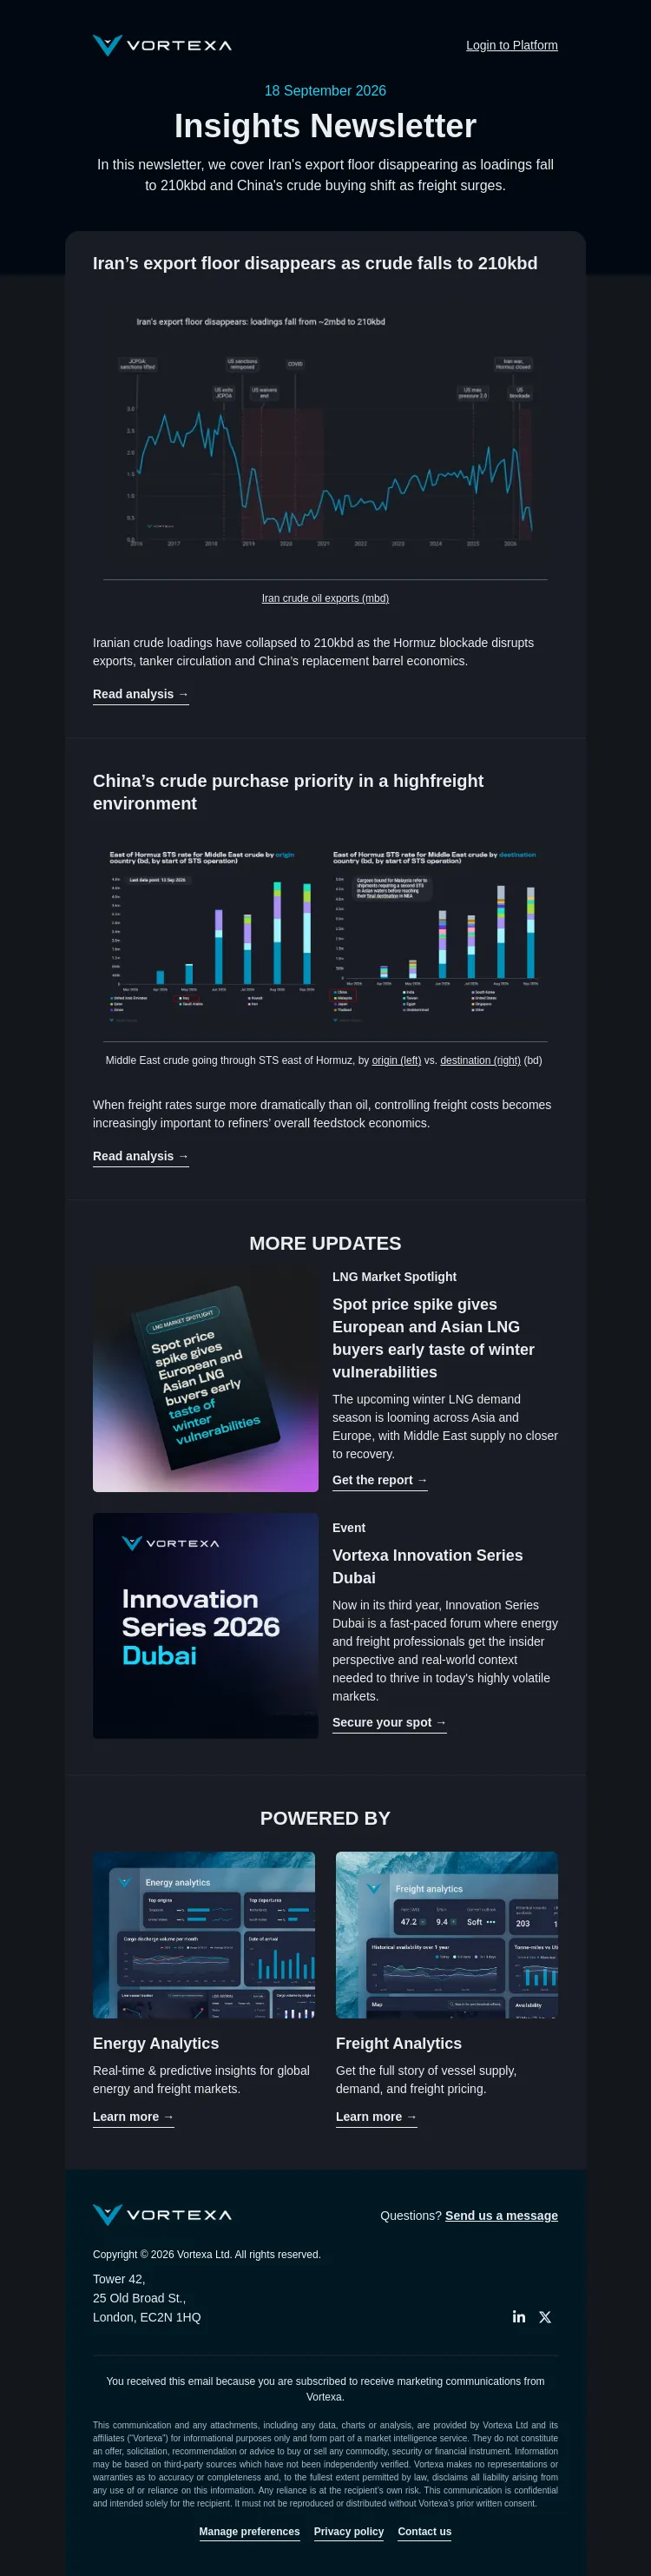
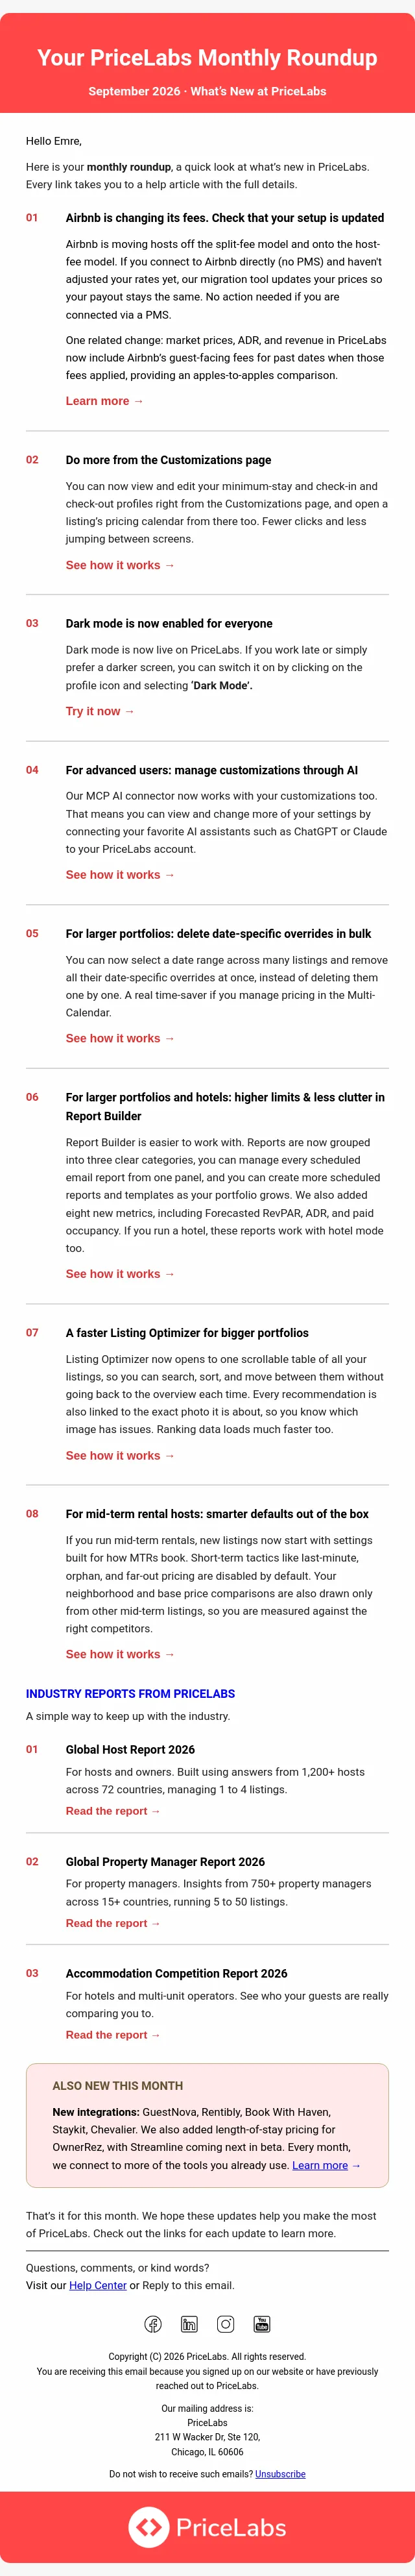
To view this email as a web page, go to the following address: https://marketinfo.vortexa.com/index.php/email/emailWebview?mkt_tok=ODM3LU1aRS01NzgAAAGkq0iVG8L_wr9GPsJ1gKugq-RvWcQlFGYWda9jv5MQVeoeJLZFkAEA23ki2LqWhGi145P6Y-jzqIo5esakMsL9L-EuWoXGmPxzLKL1eGUR7MQ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG6H3_8bs6gQD-bXXwIzPe8oE-nFwrCFN1kuYs721UosxJ2zOOaMCtWsvYwnRPz6BSac=) 5 October 2026LNG Weekly Distilling what matters in the global LNG market right nowIn partnership with KayrrosLast week at a glanceAtlantic basinPacific basinDemandEurope’s LNG arrivals stable, as governments issue mandates to support winter gas and LNG inventoriesAsia’s LNG imports bolstered by India’s near-record-high weekly arrivalsSupplyUS LNG exports steady, despite Cove Point outage; Golden Pass loads 10th cargoStrongest week for Qatari cargoes transiting out via Hormuz since US-Iran war began FOCUS TOPICLNG import flows by destination region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG9kcAqlS1c3rYecj-63n6HBJjw8A9e2pdDNNDLApdKrZlrAauWMKHUN5nN8lW9nh-Lw=) (clients only). Import comparison is to same period last year. * ‘Last 4 weeks’ reference period = 7 September-4 October 2026. ** JKT = Japan, Korea and Taiwan. Asia’s LNG imports boosted by near-record-high arrivals in India; deliveries to China slip during Golden Week holiday Last week's aggregate Asia arrivals (5.1 mt, 80 cargoes) were about 5% above their four-week average. Regional spot prices fell for a second consecutive week to an average of US$25.2/MMBtu†, the lowest level in a month. However, elevated prices did not hamper imports to India (0.9 mt, 14 cargoes), which were close to their all-time weekly high thanks to government-backed purchases for fertiliser production and stronger LNG use from the city gas sector. Elsewhere in South and Southeast Asia, Thailand’s volumes (0.4 mt, five cargoes) rebounded after last week’s flood-related disruption, and were almost 25% above their four-week average. In contrast, Pakistan did not receive any cargoes last week. In Northeast Asia, deliveries to Japan (1.1 mt, 18 cargoes) were nearly 5% higher than their four-week average. LNG inventories held by the country’s major power producers were about 20% above their five-year September average, which has weighed on LNG demand. South Korea’s receipts (1.0 mt, 15 cargoes) exceeded their four-week average by more than 10%, while shipments to China (0.9 mt, 14 cargoes) were at their lowest since early August due to a weeklong national holiday. Europe’s LNG arrivals mostly stable; Spanish and German governments issue mandates to boost inventories for winter Europe-wide LNG deliveries (2.0 mt, 35 cargoes) were almost 5% above their four-week average amid a marginal inter-basin arbitrage for flexible Atlantic cargoes to Asia. Weekly average spot LNG prices in Northeast Asia were at a US$1.4/MMBtu† premium to Northwest Europe, narrowing by over 30% week-on-week. France’s weekly receipts (0.4 mt, seven cargoes) were at their strongest since April. The country’s 1.2 mtpa Fos Tonkin LNG terminal is scheduled to complete planned maintenance on 5 October and did not receive any cargoes for the third consecutive week. Volumes to the Netherlands (0.4 mt, six cargoes) and Germany (0.1 mt, two cargoes) each surpassed their respective four-week averages by about 15%. Imports to the latter will be supported by the German government’s directive to SEFE to buy and inject 8 TWh of gas (0.6 mt of LNG equivalent) into underground storage by 15 December. Meanwhile, no conventional-sized cargoes arrived in the UK and Belgium for the first time in two weeks. In the Mediterranean, shipments to Italy (0.2 mt, four cargoes) were around 5% below their four-week average, while Spain’s receipts (0.4 mt, six cargoes) were more than 25% above the same metric. The Spanish government has raised mandated LNG inventory levels for this winter, which is expected to underpin seasonal imports. EU-wide gas storage fill ended last week at 72%, trailing the five-year average by 15 percentage points. Aggregate EU LNG send-out averaged approximately 3,600 GWh/d, consistent with its four-week average. FOCUS TOPICLNG export flows by supply region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG_nEwtoZvw40EGCzkOTWSv3Mf68zH-c-5yBrhjHBCtVPAIf72mxrQBsXNMiJlDm2H-Y=) (clients only). Export comparison is to preceding 4 weeks in current year. * ‘Last 4 weeks’ reference period = 7 September-4 October 2026. Hormuz LNG traffic maintains recent upward momentum; outbound transits by Qatari cargoes climb to highest since start of US-Iran conflict Eleven LNG carriers made confirmed Hormuz transits last week – up slightly from the four-week average of nine to 10 crossings. There were eight laden outbound transits and three ballast inbound crossings. The former included at least seven Qatari cargoes, two of which – the Milaha Qatar and Al Sadd vessels – have already discharged in India. Two other Qatari cargoes, in transit on Al Gharrafa and Al Gattara, are respectively declaring for Singapore and Zhejiang (China). There were also two more ‘dark’ STS transfers east of Hormuz, off Oman’s Sohar port, for cargoes that had exited the chokepoint – continuing the trend that has emerged since August. Qatar’s Ras Laffan terminal loaded four cargoes (0.3 mt) last week, more than 20% below its four-week average. All four of the laden carriers are still currently west of Hormuz. Meanwhile, two other Qatari cargoes (0.2 mt) unloaded in Kuwait, on the Qtaifan and Umm Al Amad carriers. In the UAE, there was one ‘dark’ load at the Das Island terminal last week, by the Mraweh steam carrier. Elsewhere, ADNOC’s Mubaraz vessel delivered a UAE-origin cargo to India’s Ennore LNG terminal, while the Gas Garuda carrier will also shortly arrive in India, to Hazira port. US LNG exports stable, including Golden Pass’s 10th cargo; planned outage continues at Cove Point terminal Last week, US supply (2.5 mt, 35 cargoes) was in line with its four-week moving average. Scheduled downtime continued at the Cove Point facility, which did not export any cargoes for the second consecutive week. Meanwhile, the Golden Pass terminal loaded its 10th cargo since its April launch, onto the QatarEnergy-controlled Umm Al Houl carrier. In September, Golden Pass exports averaged about 30% of its first train’s 6 mtpa nameplate capacity. Volumes from Australia (1.5 mt, 22 cargoes) were also consistent with their four-week average, although output from the Gladstone terminal (0.1 mt, one cargo) fell to its lowest since August. No cargoes were lifted from the Prelude FLNG facility for the fourth consecutive week, with just a single early September cargo since its return from a multi-month maintenance period. Elsewhere, shipments from Oman (0.2 mt, two cargoes) were almost 10% below their four-week average amid a planned one-train outage since the start of September. In contrast, Nigeria’s weekly exports (0.4 mt, six cargoes) strengthened to their highest since H1. † Price commentary based on Argus Media group weekly average price data. FOCUS TOPICLNG Market SpotlightFocus topic chart (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG2G1otbtX1qJVVkgHTMalgeuLwb6At7qxtamXg2AqkDKopViJbtUIEKflNSy4HOr16g=) Source: Vortexa, KayrosDaily data from the last 3 months - updated for 26 January 2026 The latest edition covers the spike in regional spot LNG prices, which hit their highest in over three years. We also assess: how Qatar and the UAE have utilised STS activity east of Hormuz to focus transit risk on older steam carriers; why seasonal competition for marginal Atlantic-origin cargoes will remain turbulent even though the inter-basin arbitrage has consistently pointed to Europe over recent weeks; and the reasons behind the constrained near-term outlook for longer Atlantic-to-Asia voyages.LNG trade flow intelligence Trusted insights into the global LNG marketLNG intelligence dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG8-zNwQV19mUV4fmB35R_Nz5O4S8DkMWbMjarpwodyJaebxYsEpEs-nmBoru-MSTiCo=) LNG Analytics Data-driven flows analytics with a competitive edge to spot short-term changes. Find out more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG8-zNwQV19mUV4fmB35R_Nz5O4S8DkMWbMjarpwodyJaebxYsEpEs-nmBoru-MSTiCo=) Outage report dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG4rGFbHTgakLD35777uglYpfU8GgTKl30wUt4jjCmF-UKil_nSxp_4vgki1UYvjm5DU=) Integrations Integrate Vortexa’s market fundamentals into your workflows via our API, Python SDK, and Excel add-in. Learn more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG4rGFbHTgakLD35777uglYpfU8GgTKl30wUt4jjCmF-UKil_nSxp_4vgki1UYvjm5DU=) Vortexa Energy Flows Analytics End to end transparency on seaborne energy flows.Start exploring (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG68UxhLgRSY0-Gqz8zi1-fg2JpJi7PfwZYYTruw-ZZ47niVm2A4LgsW9vl4ooz8Tp7g=) Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG6H3_8bs6gQD-bXXwIzPe8oE-nFwrCFN1kuYs721UosxJ2zOOaMCtWsvYwnRPz6BSac=) Questions? Send us a message (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVGxFrn3ElG7fFcsiXWLHTyplWiYv96cRjyKLz5JkhuBIGodxOSAFib99SREN4vSIbqLo=) Copyright © 2026 Vortexa Ltd. All rights reserved. Tower 42,25 Old Broad St.,London, EC2N 1HQLinkedIn (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG0tT-O22FkVP1cn0-uDt0WHtKLwoKe86tKFGMWcf762ARCM8mVreQe9D2elGVDl-LTA=) X (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG4jEVmIujwC7axhgpZ_rKIeXxSvQ0Uzvf9WchcPUenaw8PRUL2i1HyiY1rSmzvRWv9M=) You received this email because you are subscribed to the Vortexa Newsletter This communication and any attachments, including any data, charts or analysis, are provided by Vortexa Ltd and its affiliates (“Vortexa”) for informational purposes only and form part of a market intelligence service. They do not constitute an offer, solicitation, recommendation or advice to buy or sell any commodity, security or financial instrument. Information may be based on third-party sources which have not been independently verified. Vortexa makes no representations or warranties as to accuracy or completeness and, to the fullest extent permitted by law, disclaims all liability arising from any use of or reliance on this information. Any reliance is at the recipient’s own risk. This communication is confidential and intended solely for the recipient. It must not be reproduced or distributed without Vortexa’s prior written consent. Manage preferences (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVGzReXru4MdkuBeALWOVf2Hyr0I5Dvwp21RPThsG-xqtoeu0O9HltBmfgykj6LmxXTPY=) Privacy policy (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVG-RcL1sv7GSgrWXfqfUW9n9HUiUkpwlJ6RJDBLFeTEHr0TxFDef7n2mvqwlNNwfudxw=) Contact us (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkq0iVGxFrn3ElG7fFcsiXWLHTyplWiYv96cRjyKLz5JkhuBIGodxOSAFib99SREN4vSIbqLo=) .
- Accession
- nse/vortexa/2026-10-05/3204
- From
- Vortexa · analysts@vortexa.com
- Sent
- 5 October 2026 · 13:00 UTC