Vortexa LNG Weekly
Distilling what matters in the global LNG market right now.
- Product
- Vortexa
- Sent from
- vortexa.com
- Sent
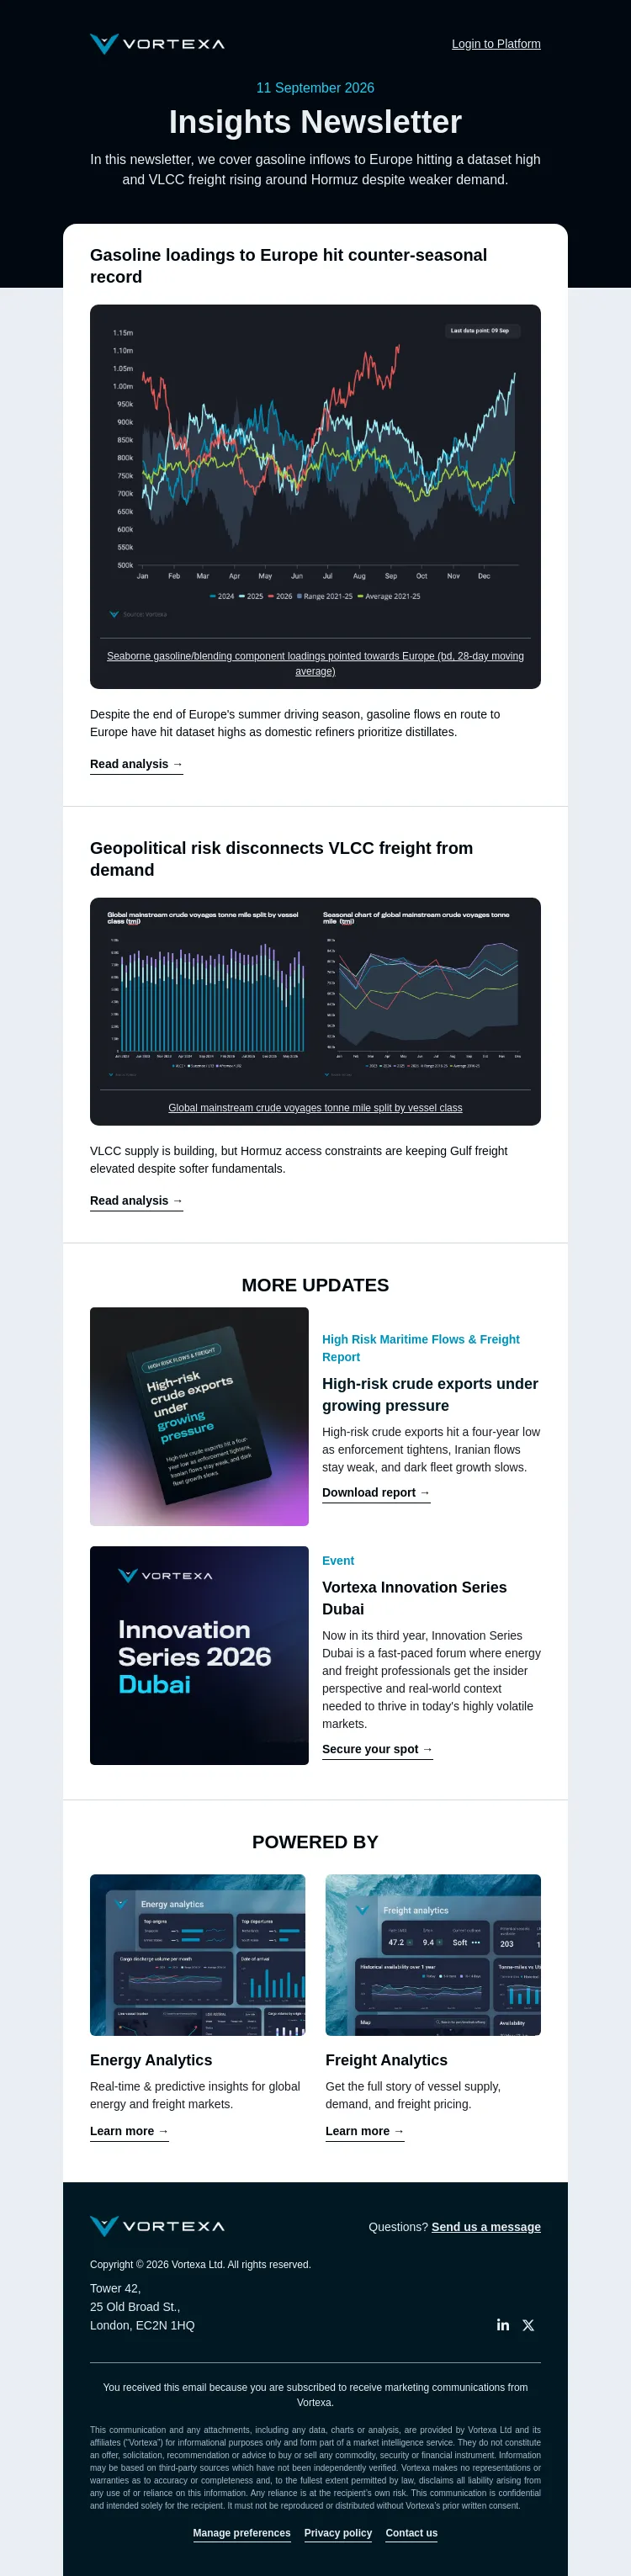
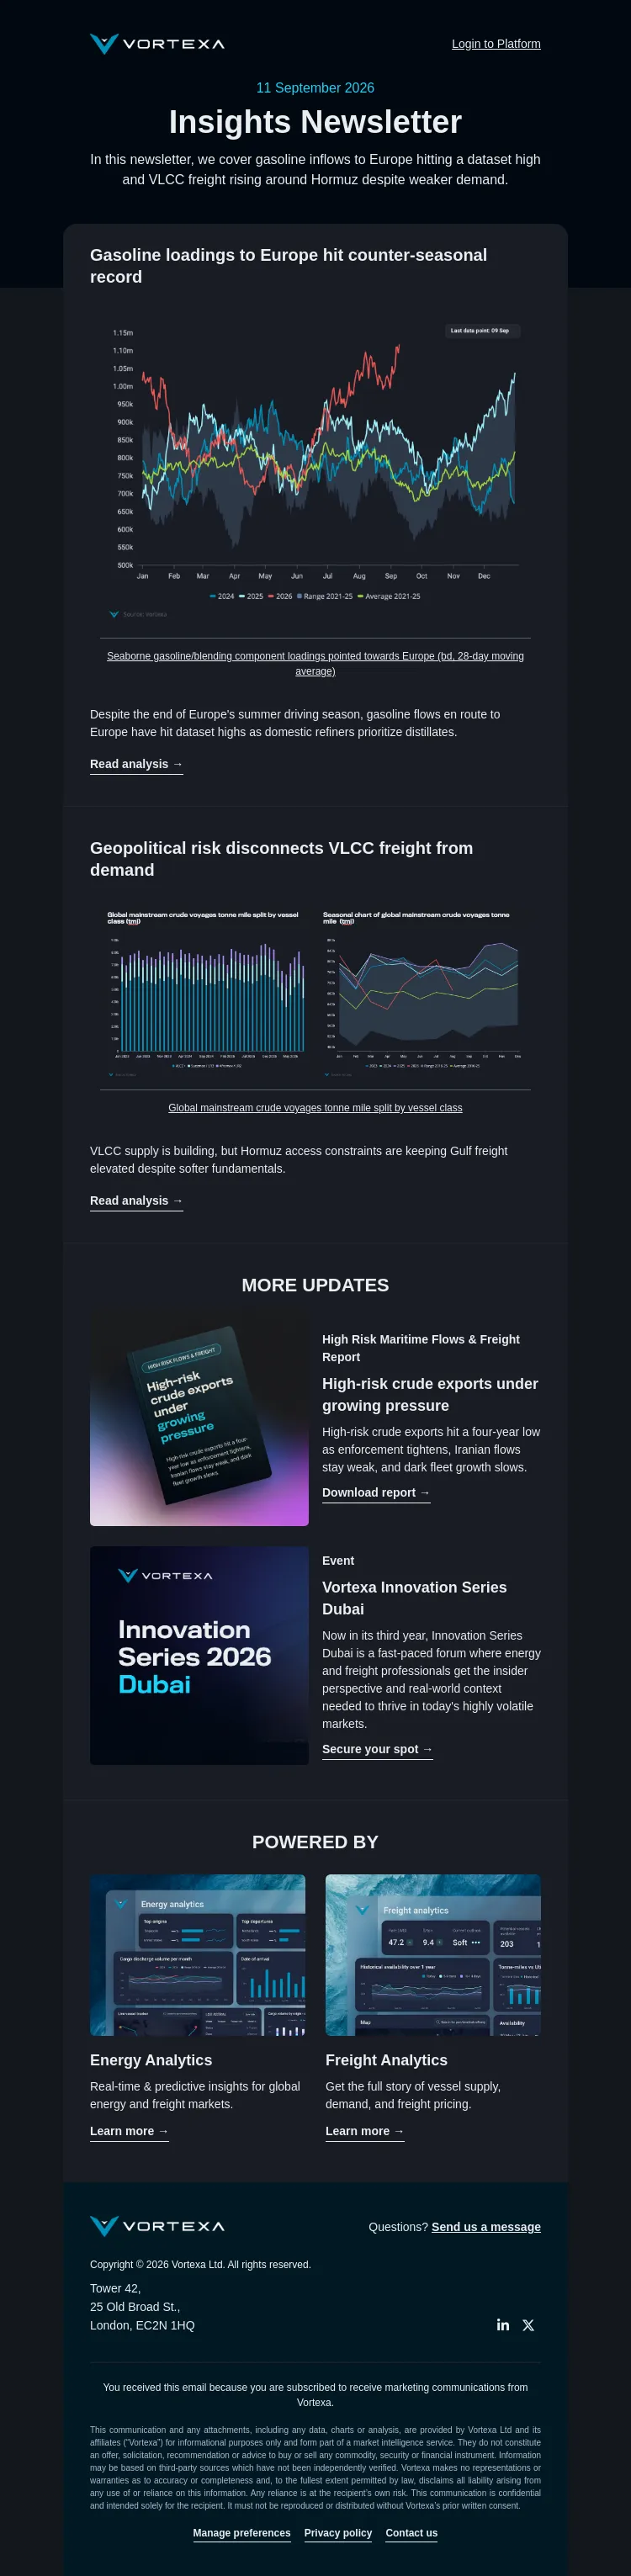
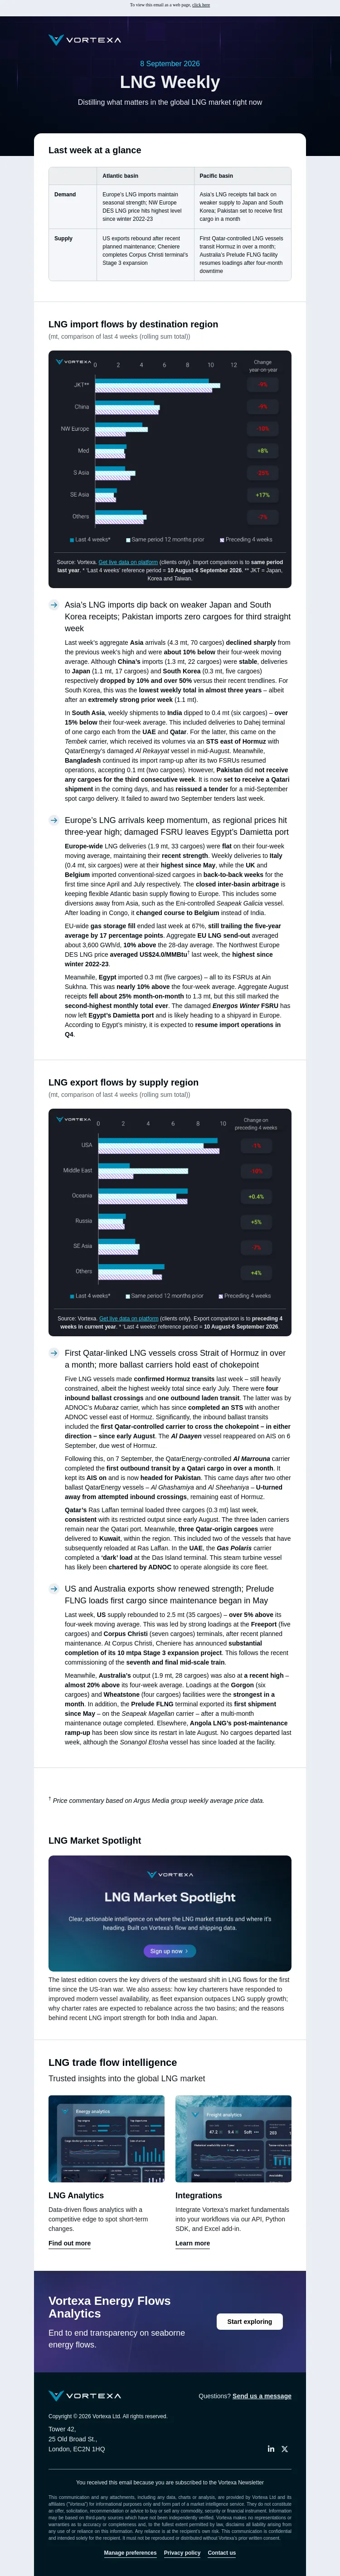
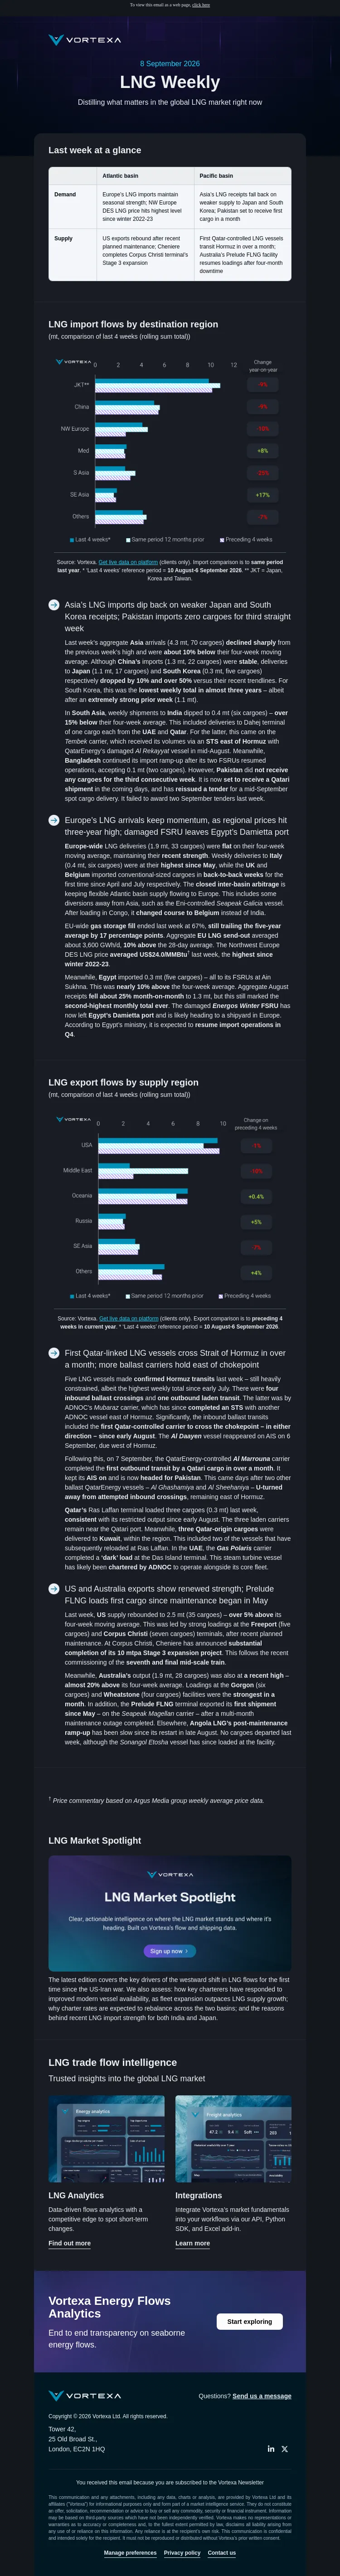
To view this email as a web page, go to the following address: https://marketinfo.vortexa.com/index.php/email/emailWebview?mkt_tok=ODM3LU1aRS01NzgAAAGkRNLDdsmcbY20OWBs7Wf1XQH5EnNldObukfgQi5Ql85Bt_Z8QyHMpDvEboaO6_J-2urrXmNFWenpFbsRmwIsrdaIaFkleoaCJiUQMGvLBWKE ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdqwdI3nkBSGoZ2KsP2QCBCBFR2361ViBOvTtkzMcsn4WualbTjoPqpVBO-cUPGXYGtk=) 15 September 2026LNG Weekly Distilling what matters in the global LNG market right nowIn partnership with KayrrosLast week at a glanceAtlantic basinPacific basinDemandEuropean buyers increase bids after inter-basin arbitrage marginally reopens to Asia; multi-year price highs for NW Europe DES LNG and regional gas hubsAsia spot LNG prices rise to highest in over three years, challenging price-sensitive procurement; Pakistan receives first cargo in a month, from QatarSupplyUS exports up slightly week-on-week, led by Plaquemines; Trinidad and Tobago loadings strongest since summer downtimeLimited Hormuz LNG traffic includes two outbound Qatari cargoes; Oman LNG terminal undergoes planned maintenance FOCUS TOPICLNG import flows by destination region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdgfiWj2cx5Wjm73LTiggEtNUYvpYTFLAYhIQ2hnXgXHCo4AFGcyNv_OV-ra6e7gnpLs=) (clients only). Import comparison is to same period last year. * ‘Last 4 weeks’ reference period = 17 August-13 September 2026. ** JKT = Japan, Korea and Taiwan. Asia’s LNG imports weaken as regional spot prices hit highest level since late 2022, sidelining some buyers Last week’s aggregate Asia arrivals (4.2 mt, 68 cargoes) fell sharply for the second consecutive week, down nearly 10% on their four-week moving average. This was led by weaker imports to China (0.9 mt, 14 cargoes) and Taiwan (0.4 mt, six cargoes) – respectively almost 20% and 15% below their recent trends. Receipts in Japan (1.2 mt, 21 cargoes) and South Korea (0.7 mt, 10 cargoes) were more stable. Regional spot prices increased to an average of nearly US$27/MMBtu† last week, which has inevitably resulted in key price-sensitive Asian buyers cooling interest in related prompt purchases. This includes India, although several upcoming spot cargoes were reportedly secured at premium prices. India received one UAE-sourced cargo last week – on the Gas Polaris vessel after its ‘dark’ outbound Hormuz transit – and will shortly receive another on the Umm Al Ashtan carrier. Meanwhile, Pakistan received its first cargo in four weeks – a Qatari shipment on the Al Marrouna vessel, which recently crossed Hormuz with its AIS on. Europe’s LNG arrivals dip, as competition from Asia keeps inter-basin arbitrage more finely balanced Europe-wide LNG deliveries (1.5 mt, 30 cargoes) declined to their weakest since July, down over 15% on the four-week moving average. This was despite relatively strong arrivals to France (0.4 mt, six cargoes) – up 6% on their recent trendline. The UK and Belgium once again did not import any conventional-sized cargoes. On 15 September, French unions held strikes that affected operations at the Fluxys-operated Dunkirk LNG import terminal. In the first half of last week, the inter-basin arbitrage for flexible US cargoes was considered marginally open to Asia. It subsequently closed again after bids from European buyers increased. The Northwest Europe DES LNG price rose further last week to an average of US$26.1/MMBtu† – a level last seen in winter 2022-23. EU-wide gas storage fill ended the week at 68%, still trailing the five-year average by 16 percentage points. Aggregate EU LNG send-out averaged about 3,300 GWh/d, in line with its 28-day average. Meanwhile, Egypt imported 0.3 mt (four cargoes) – all to its FSRUs at Ain Sukhna. This was over 15% below the four-week average, despite the country’s ongoing gas demand for seasonal cooling. The laden Orion Sirius vessel diverted away from Egypt towards Europe last week, U-turning in the Mediterranean. The carrier is now holding off Spain ahead of its discharge. The damaged Energos Winter FSRU, which recently left Egypt’s Damietta port, has also arrived in Spain for repairs at a shipyard at Ferrol. It is intended to resume import operations in Egypt in Q4. FOCUS TOPICLNG export flows by supply region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdmaL9i29OSTzln0LhWguDn9lifMzKRkJDGDmIkmNDGQrDmdvlY_ptsNrcYYX8jl4nhc=) (clients only). Export comparison is to preceding 4 weeks in current year. * ‘Last 4 weeks’ reference period = 17 August-13 September 2026. Hormuz LNG traffic remains sporadic, including Qatar-linked carriers; UAE ‘dark’ loadings continue, using vessels on Iran’s ‘non-compliant’ list Five LNG carriers made confirmed Hormuz transits last week – down slightly from the previous week’s two-month high (seven crossings). There were three laden outbound transits and two inbound ballast crossings. The former included two Qatari cargoes, one of which – the Al Rayyan vessel – has since engaged in a ‘dark’ STS with another QatarEnergy-controlled carrier off Oman. Qatar’s Ras Laffan terminal loaded five cargoes (0.4 mt) last week, about 20% above its recent constrained average. The five laden carriers are all still currently west of Hormuz, including Shandong Redwood, which had previously been off AIS since early August. Meanwhile, in addition to the Al Marrouna’s discharge in Pakistan, another two Qatar-origin cargoes were delivered to Kuwait, within the region. In recent days, the GasLog Savannah vessel has also offloaded Qatari volumes in Thailand, having recently received its cargo via an STS from the damaged GasLog Shanghai carrier. In the UAE, there were two more ‘dark’ loads at the Das Island terminal, by ADNOC’s Umm Al Ashtan and Marigold LNG steam carriers. Umm Al Ashtan has since completed its latest ‘dark’ outbound Hormuz crossing and is now waiting to discharge in west India. The ADNOC-chartered Gas Polaris carrier delivered a UAE cargo to Dahej in India last week. US and Australia exports broadly stable; Oman LNG output dips on maintenance Last week, US supply (2.6 mt, 36 cargoes) rose 4% above its four-week moving average. This was led by strong loadings at the Plaquemines terminal (0.6 mt, eight cargoes) – the most in two months. In contrast, Australia’s output dipped slightly to 1.6 mt (23 cargoes), with exports from the Wheatstone facility (0.1 mt, two cargoes) falling more than 25% below their recent average. Elsewhere, Oman’s LNG loadings (0.2 mt, two cargoes) declined to their lowest weekly level in almost a year, owing to planned September maintenance at Train 1 of its three-train terminal. In contrast, Trinidad and Tobago exports have normalised after Atlantic LNG Train 4’s scheduled summer downtime, with output reaching 0.4 mt (five cargoes) last week. Meanwhile, Russia’s LNG flows included the first discharge by the new Konstantin Posiet vessel – the third Arc7 ice-class carrier for the sanctioned Arctic LNG 2 project. It delivered its maiden cargo to the domestic Koryak floating storage unit in Russia’s Far East. † Price commentary based on Argus Media group weekly average price data. FOCUS TOPICLNG Market SpotlightFocus topic chart (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdhgy6LoDlfrHvzOwKzKUjGLPibOjXUPanCKjIDRi63pohZp0D_LNFecuecPJmsP-Duo=) Source: Vortexa, KayrosDaily data from the last 3 months - updated for 26 January 2026 The latest edition covers the key drivers of the westward shift in LNG flows for the first time since the US-Iran war. We also assess: how key charterers have responded to improved modern vessel availability, as fleet expansion outpaces LNG supply growth; why charter rates are expected to rebalance across the two basins; and the reasons behind recent LNG import strength for both India and Japan.LNG trade flow intelligence Trusted insights into the global LNG marketLNG intelligence dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDduqHsWdX4wvBwMshCskpEtKAVX13i4vCuYhOgMVK66y8ntTyceC62L252HSNQHONrsE=) LNG Analytics Data-driven flows analytics with a competitive edge to spot short-term changes. Find out more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDduqHsWdX4wvBwMshCskpEtKAVX13i4vCuYhOgMVK66y8ntTyceC62L252HSNQHONrsE=) Outage report dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdq81WS-An93IakGFB-kCTZ3EbpMNEZKTYySYMQ-4plhMPBbV-DwNlArPrb24nLuI2Nk=) Integrations Integrate Vortexa’s market fundamentals into your workflows via our API, Python SDK, and Excel add-in. Learn more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdq81WS-An93IakGFB-kCTZ3EbpMNEZKTYySYMQ-4plhMPBbV-DwNlArPrb24nLuI2Nk=) Vortexa Energy Flows Analytics End to end transparency on seaborne energy flows.Start exploring (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdu7hhtjRGXySGfXUdnj3rgbMj9y2Sfx703mTnGAfrLv2P5teGeWpivcp3-9Myz1NxRY=) Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdqwdI3nkBSGoZ2KsP2QCBCBFR2361ViBOvTtkzMcsn4WualbTjoPqpVBO-cUPGXYGtk=) Questions? Send us a message (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdq33EttliHzF4mu5vgsqp_1ODs9y5UFh-acvOnMBXqM9D8zSizr6_NaTCKwJ6coQ0ug=) Copyright © 2026 Vortexa Ltd. All rights reserved. Tower 42,25 Old Broad St.,London, EC2N 1HQLinkedIn (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdrrLAVXYm8osENJuH-PkvLNE0ewjHjjTAcr8GdK0RBAZ2YvEwfjGb7nwECw56YrJW9E=) X (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdgn0UCRWaQ_TA-3iGEOJpyPICI9GFadwpATU1RzurfBiUAq5PdAFshK0KXjQu8a9lcY=) You received this email because you are subscribed to the Vortexa Newsletter This communication and any attachments, including any data, charts or analysis, are provided by Vortexa Ltd and its affiliates (“Vortexa”) for informational purposes only and form part of a market intelligence service. They do not constitute an offer, solicitation, recommendation or advice to buy or sell any commodity, security or financial instrument. Information may be based on third-party sources which have not been independently verified. Vortexa makes no representations or warranties as to accuracy or completeness and, to the fullest extent permitted by law, disclaims all liability arising from any use of or reliance on this information. Any reliance is at the recipient’s own risk. This communication is confidential and intended solely for the recipient. It must not be reproduced or distributed without Vortexa’s prior written consent. Manage preferences (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdmqcpADlo_z9ulggzNPrERpSA21p2ZLGL_fhLuWv_2LWtYDYKQo3eMXmn8HyogKI7ho=) Privacy policy (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdrjPnfWFLJ8yQxFlEDpfx4HoQ-4xjly6ac64VUw7It_Ni6PA4unjmKV9g87enbhlnSE=) Contact us (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkRNLDdq33EttliHzF4mu5vgsqp_1ODs9y5UFh-acvOnMBXqM9D8zSizr6_NaTCKwJ6coQ0ug=) .
- Accession
- nse/vortexa/2026-09-15/1567
- From
- Vortexa · analysts@vortexa.com
- Sent
- 15 September 2026 · 16:00 UTC