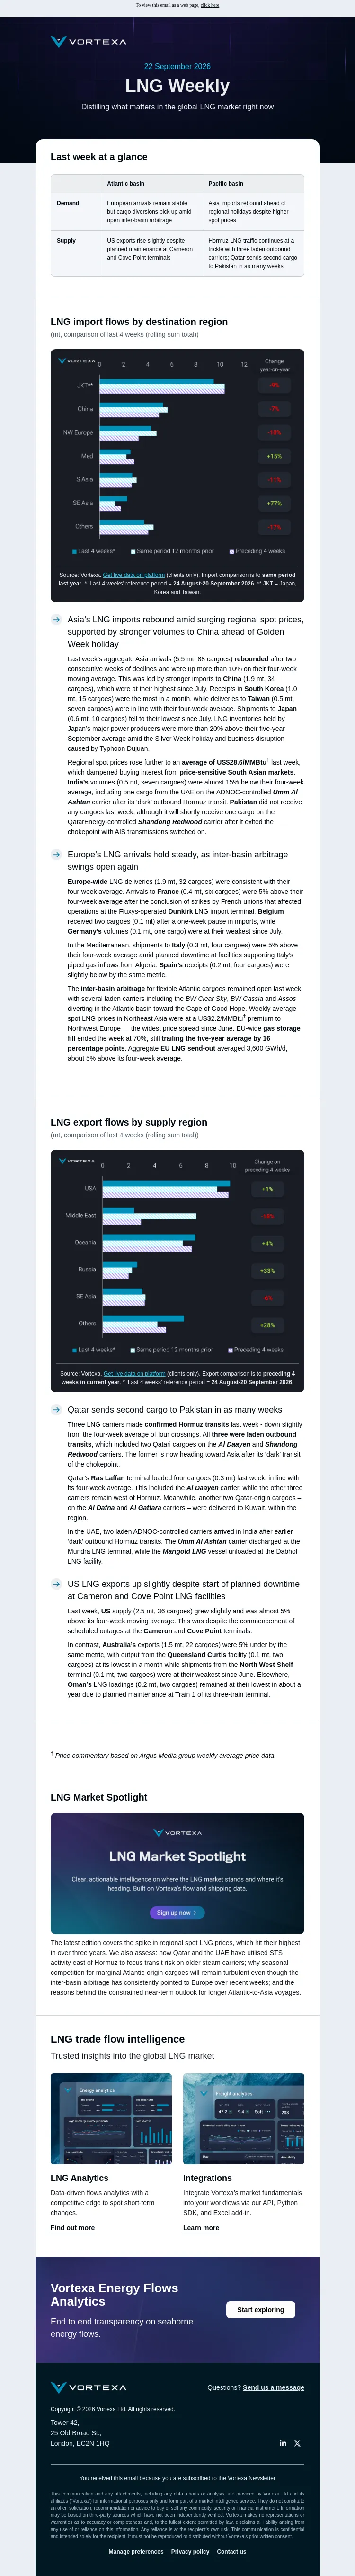
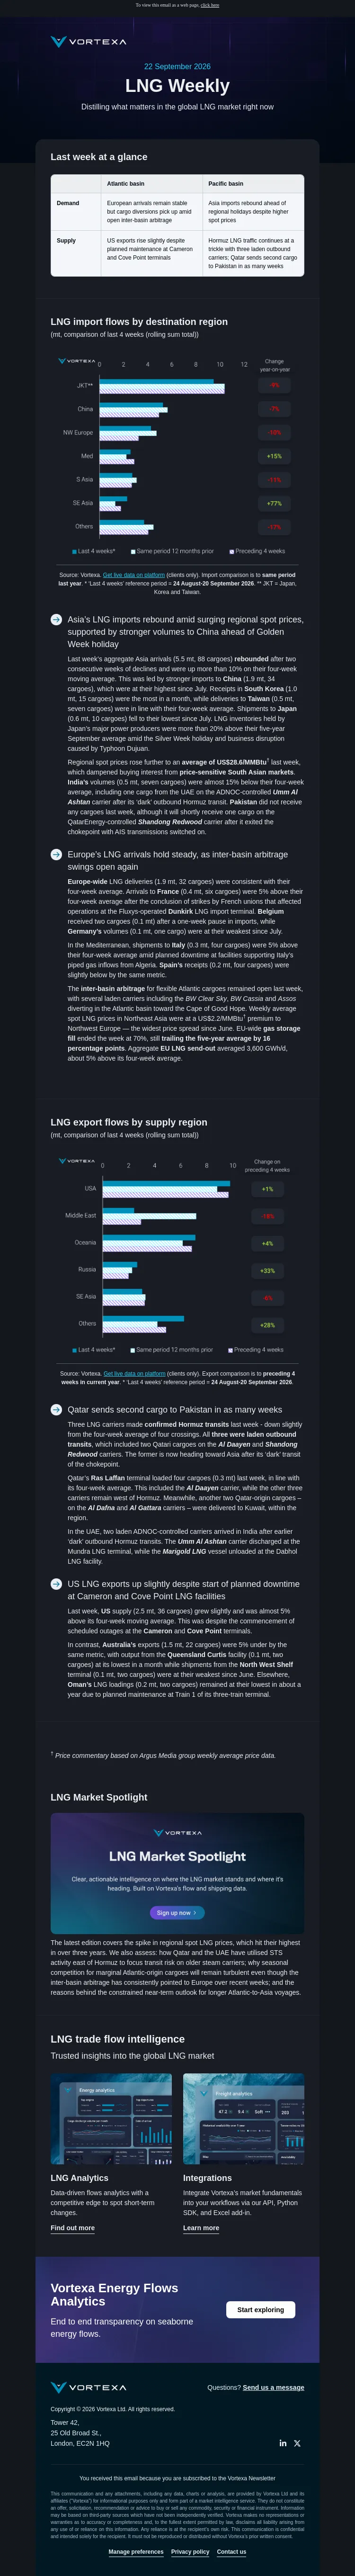
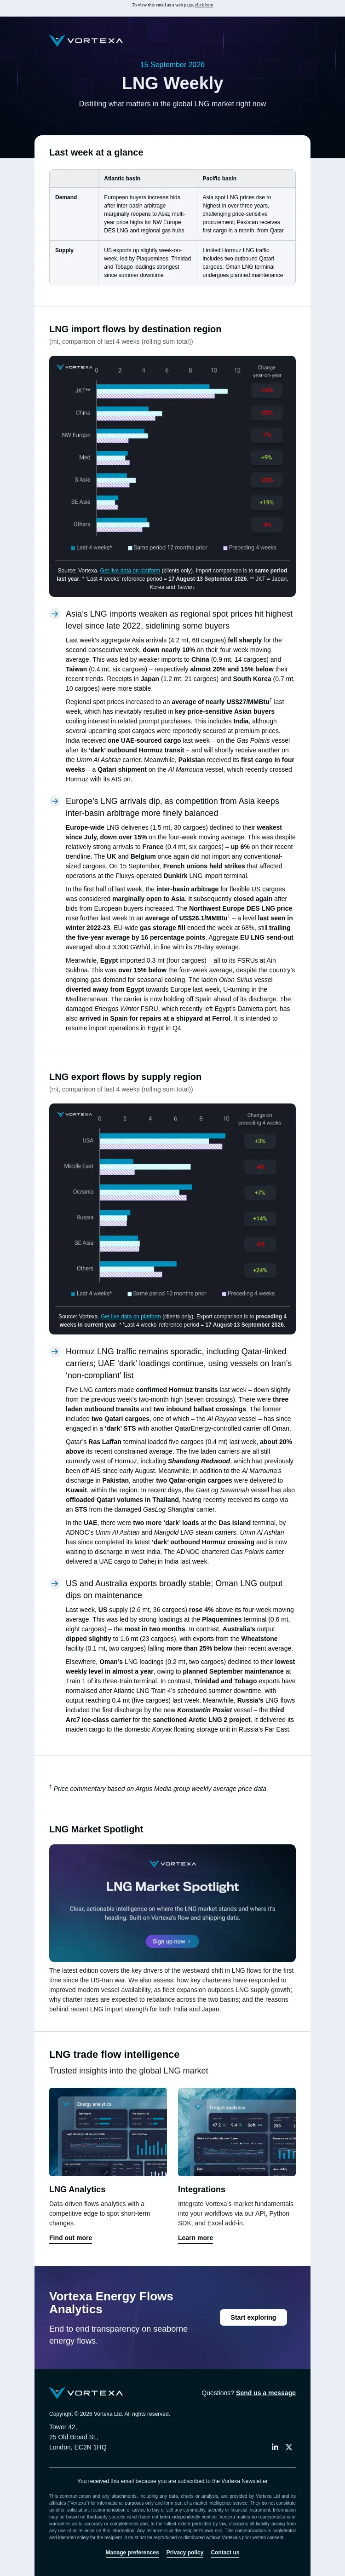
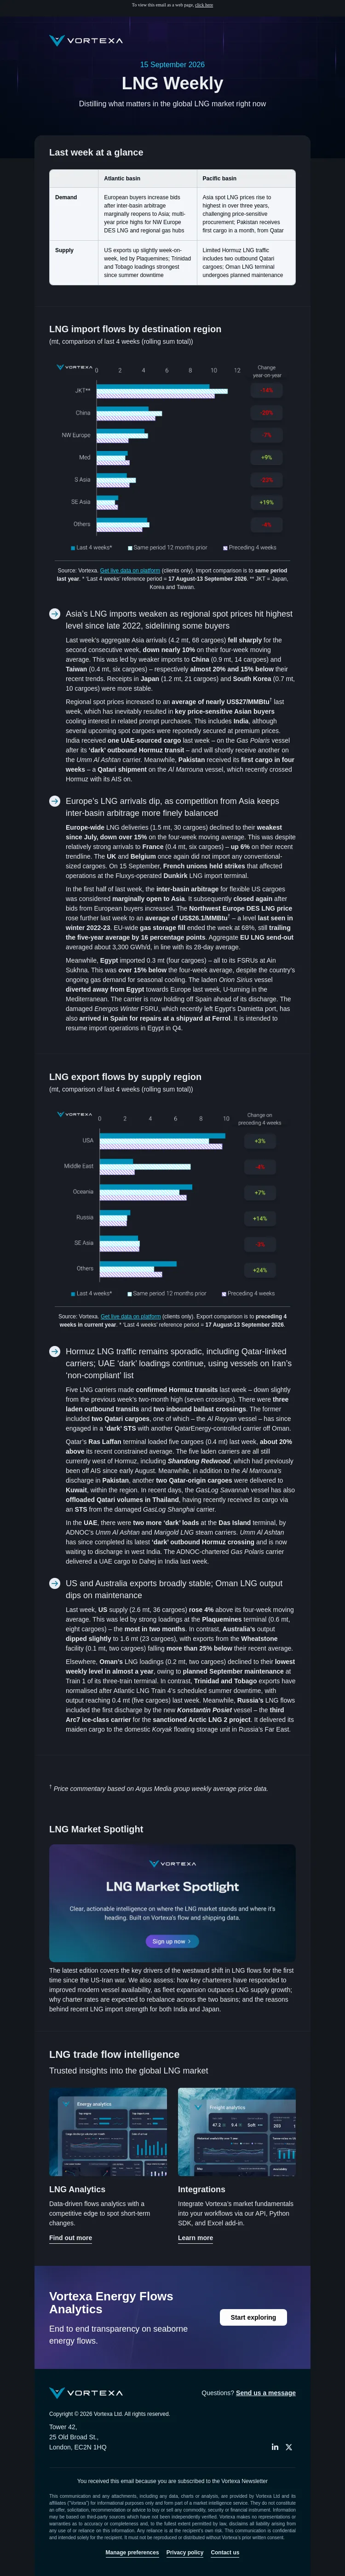
Vortexa LNG Weekly
Distilling what matters in the global LNG market right now.
- Product
- Vortexa
- Sent from
- vortexa.com
- Sent
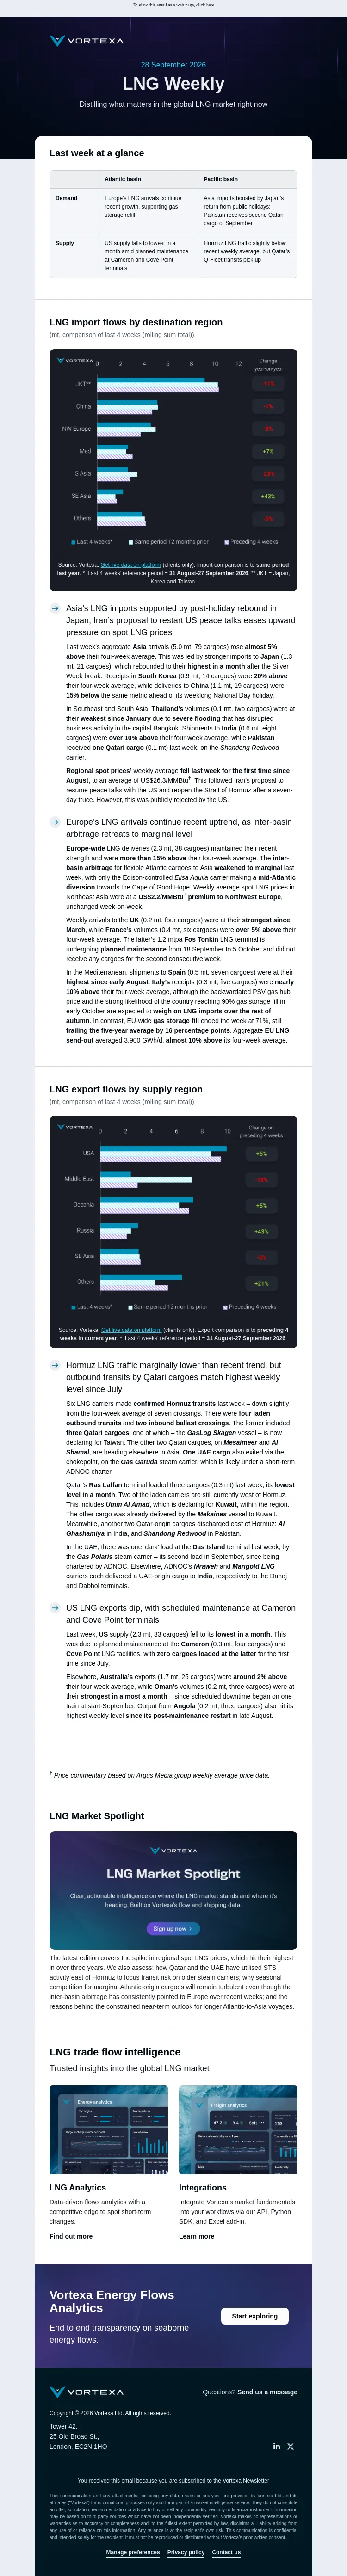
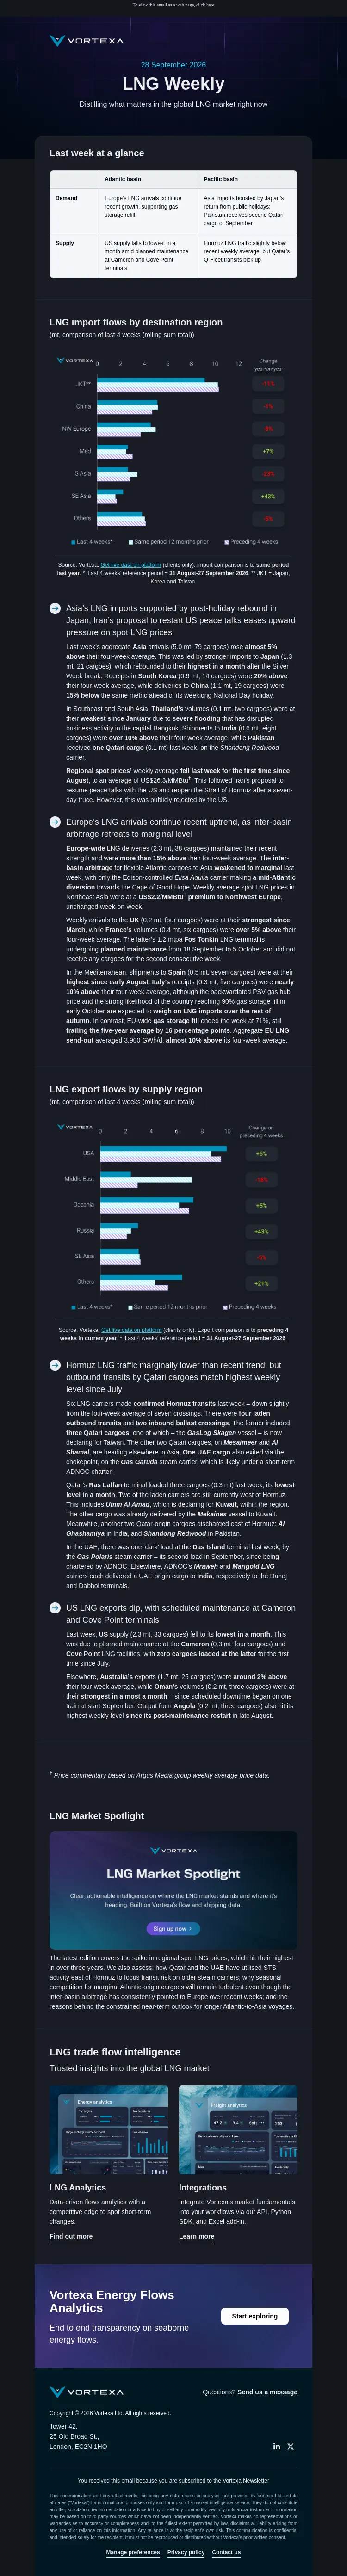
To view this email as a web page, go to the following address: https://marketinfo.vortexa.com/index.php/email/emailWebview?mkt_tok=ODM3LU1aRS01NzgAAAGkILirJYPi-6mq8p72rbLuFg0cKsB7Jlh_UACEe8z7hi2vT-XH40nj5tRycnWpu6umcuMGAtJwer7ZJwDfvs4lqa1uU0XeAuJNchwdbIyN2Ik ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJTwZFtgCHbsSHmVLquU1i5l_qVx9cUn1zCmYXN64sa6upHYEB4WOz8WYVaDbpq1JiGA=) 8 September 2026LNG Weekly Distilling what matters in the global LNG market right nowIn partnership with KayrrosLast week at a glanceAtlantic basinPacific basinDemandEurope’s LNG imports maintain seasonal strength; NW Europe DES LNG price hits highest level since winter 2022-23Asia’s LNG receipts fall back on weaker supply to Japan and South Korea; Pakistan set to receive first cargo in a monthSupplyUS exports rebound after recent planned maintenance; Cheniere completes Corpus Christi terminal’s Stage 3 expansionFirst Qatar-controlled LNG vessels transit Hormuz in over a month; Australia’s Prelude FLNG facility resumes loadings after four-month downtime FOCUS TOPICLNG import flows by destination region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJVz4Xqs2QXvHopRKGYHXkTj4hDY0YdO5q7jjjb_7vr-NqlqKot7upqtH3ht3F3IJX18=) (clients only). Import comparison is to same period last year. * ‘Last 4 weeks’ reference period = 10 August-6 September 2026. ** JKT = Japan, Korea and Taiwan. Asia’s LNG imports dip back on weaker Japan and South Korea receipts; Pakistan imports zero cargoes for third straight week Last week’s aggregate Asia arrivals (4.3 mt, 70 cargoes) declined sharply from the previous week’s high and were about 10% below their four-week moving average. Although China’s imports (1.3 mt, 22 cargoes) were stable, deliveries to Japan (1.1 mt, 17 cargoes) and South Korea (0.3 mt, five cargoes) respectively dropped by 10% and over 50% versus their recent trendlines. For South Korea, this was the lowest weekly total in almost three years – albeit after an extremely strong prior week (1.1 mt). In South Asia, weekly shipments to India dipped to 0.4 mt (six cargoes) – over 15% below their four-week average. This included deliveries to Dahej terminal of one cargo each from the UAE and Qatar. For the latter, this came on the Tembek carrier, which received its volumes via an STS east of Hormuz with QatarEnergy’s damaged Al Rekayyat vessel in mid-August. Meanwhile, Bangladesh continued its import ramp-up after its two FSRUs resumed operations, accepting 0.1 mt (two cargoes). However, Pakistan did not receive any cargoes for the third consecutive week. It is now set to receive a Qatari shipment in the coming days, and has reissued a tender for a mid-September spot cargo delivery. It failed to award two September tenders last week. Europe’s LNG arrivals keep momentum, as regional prices hit three-year high; damaged FSRU leaves Egypt’s Damietta port Europe-wide LNG deliveries (1.9 mt, 33 cargoes) were flat on their four-week moving average, maintaining their recent strength. Weekly deliveries to Italy (0.4 mt, six cargoes) were at their highest since May, while the UK and Belgium imported conventional-sized cargoes in back-to-back weeks for the first time since April and July respectively. The closed inter-basin arbitrage is keeping flexible Atlantic basin supply flowing to Europe. This includes some diversions away from Asia, such as the Eni-controlled Seapeak Galicia vessel. After loading in Congo, it changed course to Belgium instead of India. EU-wide gas storage fill ended last week at 67%, still trailing the five-year average by 17 percentage points. Aggregate EU LNG send-out averaged about 3,600 GWh/d, 10% above the 28-day average. The Northwest Europe DES LNG price averaged US$24.0/MMBtu† last week, the highest since winter 2022-23. Meanwhile, Egypt imported 0.3 mt (five cargoes) – all to its FSRUs at Ain Sukhna. This was nearly 10% above the four-week average. Aggregate August receipts fell about 25% month-on-month to 1.3 mt, but this still marked the second-highest monthly total ever. The damaged Energos Winter FSRU has now left Egypt’s Damietta port and is likely heading to a shipyard in Europe. According to Egypt’s ministry, it is expected to resume import operations in Q4. FOCUS TOPICLNG export flows by supply region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJYV1SapCXWvG85MxCUIj8T7ND6FqqzbVHDqdmYfMb3XHQDK0clt8fTMsmOgV6PGszWA=) (clients only). Export comparison is to preceding 4 weeks in current year. * ‘Last 4 weeks’ reference period = 10 August-6 September 2026. First Qatar-linked LNG vessels cross Strait of Hormuz in over a month; more ballast carriers hold east of chokepoint Five LNG vessels made confirmed Hormuz transits last week – still heavily constrained, albeit the highest weekly total since early July. There were four inbound ballast crossings and one outbound laden transit. The latter was by ADNOC’s Mubaraz carrier, which has since completed an STS with another ADNOC vessel east of Hormuz. Significantly, the inbound ballast transits included the first Qatar-controlled carrier to cross the chokepoint – in either direction – since early August. The Al Daayen vessel reappeared on AIS on 6 September, due west of Hormuz. Following this, on 7 September, the QatarEnergy-controlled Al Marrouna carrier completed the first outbound transit by a Qatari cargo in over a month. It kept its AIS on and is now headed for Pakistan. This came days after two other ballast QatarEnergy vessels – Al Ghashamiya and Al Sheehaniya – U-turned away from attempted inbound crossings, remaining east of Hormuz. Qatar’s Ras Laffan terminal loaded three cargoes (0.3 mt) last week, consistent with its restricted output since early August. The three laden carriers remain near the Qatari port. Meanwhile, three Qatar-origin cargoes were delivered to Kuwait, within the region. This included two of the vessels that have subsequently reloaded at Ras Laffan. In the UAE, the Gas Polaris carrier completed a ‘dark’ load at the Das Island terminal. This steam turbine vessel has likely been chartered by ADNOC to operate alongside its core fleet. US and Australia exports show renewed strength; Prelude FLNG loads first cargo since maintenance began in May Last week, US supply rebounded to 2.5 mt (35 cargoes) – over 5% above its four-week moving average. This was led by strong loadings at the Freeport (five cargoes) and Corpus Christi (seven cargoes) terminals, after recent planned maintenance. At Corpus Christi, Cheniere has announced substantial completion of its 10 mtpa Stage 3 expansion project. This follows the recent commissioning of the seventh and final mid-scale train. Meanwhile, Australia’s output (1.9 mt, 28 cargoes) was also at a recent high – almost 20% above its four-week average. Loadings at the Gorgon (six cargoes) and Wheatstone (four cargoes) facilities were the strongest in a month. In addition, the Prelude FLNG terminal exported its first shipment since May – on the Seapeak Magellan carrier – after a multi-month maintenance outage completed. Elsewhere, Angola LNG’s post-maintenance ramp-up has been slow since its restart in late August. No cargoes departed last week, although the Sonangol Etosha vessel has since loaded at the facility. † Price commentary based on Argus Media group weekly average price data. FOCUS TOPICLNG Market SpotlightFocus topic chart (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJcswOVXwEBF6IC5-G-BprQ-7Wuf5_Afm8vMwb499DbefEuSe190THMPgcxGvpJquzLs=) Source: Vortexa, KayrosDaily data from the last 3 months - updated for 26 January 2026 The latest edition covers the key drivers of the westward shift in LNG flows for the first time since the US-Iran war. We also assess: how key charterers have responded to improved modern vessel availability, as fleet expansion outpaces LNG supply growth; why charter rates are expected to rebalance across the two basins; and the reasons behind recent LNG import strength for both India and Japan.LNG trade flow intelligence Trusted insights into the global LNG marketLNG intelligence dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJUMOAVBkd3KgRDJV4CJJADHa-rHN2dK8_-Lmtzl7cUzJBtDpcMuOI40smpzf8aGhn08=) LNG Analytics Data-driven flows analytics with a competitive edge to spot short-term changes. Find out more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJUMOAVBkd3KgRDJV4CJJADHa-rHN2dK8_-Lmtzl7cUzJBtDpcMuOI40smpzf8aGhn08=) Outage report dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJQc4WFfxqMEnZkdoqd_CQkQx7-QGe523WKVkd1XuC6rqCQGCQNv54-by8Rsx8biuWqI=) Integrations Integrate Vortexa’s market fundamentals into your workflows via our API, Python SDK, and Excel add-in. Learn more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJQc4WFfxqMEnZkdoqd_CQkQx7-QGe523WKVkd1XuC6rqCQGCQNv54-by8Rsx8biuWqI=) Vortexa Energy Flows Analytics End to end transparency on seaborne energy flows.Start exploring (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJdJKOXCfXIECa4yTLCI7oJX29etndJKswbW86V2OK34tNFpzDJaATr7v7tE1V4THmVk=) Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJTwZFtgCHbsSHmVLquU1i5l_qVx9cUn1zCmYXN64sa6upHYEB4WOz8WYVaDbpq1JiGA=) Questions? Send us a message (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJRwuCzdasaDJIb-NwAgaDjVqrql84sowMS_px-XxBYxymiF0z6zrUiHEHYi-DYqDZG4=) Copyright © 2026 Vortexa Ltd. All rights reserved. Tower 42,25 Old Broad St.,London, EC2N 1HQLinkedIn (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJe5JRTMYuCpdsVfKD-da2TUBbY1vLL08_DaCrem8Epb0c5kGGt9AztKCsGOyTyfhblA=) X (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJcjyGRJhNpb_smGzY5RS2-zm_QsIfmFaDIZWgFiDz5iaV8vboJesAcPDt5vDyhgw0SM=) You received this email because you are subscribed to the Vortexa Newsletter This communication and any attachments, including any data, charts or analysis, are provided by Vortexa Ltd and its affiliates (“Vortexa”) for informational purposes only and form part of a market intelligence service. They do not constitute an offer, solicitation, recommendation or advice to buy or sell any commodity, security or financial instrument. Information may be based on third-party sources which have not been independently verified. Vortexa makes no representations or warranties as to accuracy or completeness and, to the fullest extent permitted by law, disclaims all liability arising from any use of or reliance on this information. Any reliance is at the recipient’s own risk. This communication is confidential and intended solely for the recipient. It must not be reproduced or distributed without Vortexa’s prior written consent. Manage preferences (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJaK2RUXDfLAIwFHR8M8eqs9NnJQyE5zAhlrrJsFurlKKEbhPZDc1DNf2WzxXFI4wXzg=) Privacy policy (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJYPVQobEapL2ATHgU6FkxPUqwT_5IiFymGcE2Q6WaecRStDDo2Zd4n-_XvbuSsgnJec=) Contact us (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGkILirJRwuCzdasaDJIb-NwAgaDjVqrql84sowMS_px-XxBYxymiF0z6zrUiHEHYi-DYqDZG4=) .
- Accession
- nse/vortexa/2026-09-08/927
- From
- Vortexa · analysts@vortexa.com
- Sent
- 8 September 2026 · 16:00 UTC