Vortexa LNG Weekly
Distilling what matters in the global LNG market right now.
- Product
- Vortexa
- Sent from
- vortexa.com
- Sent
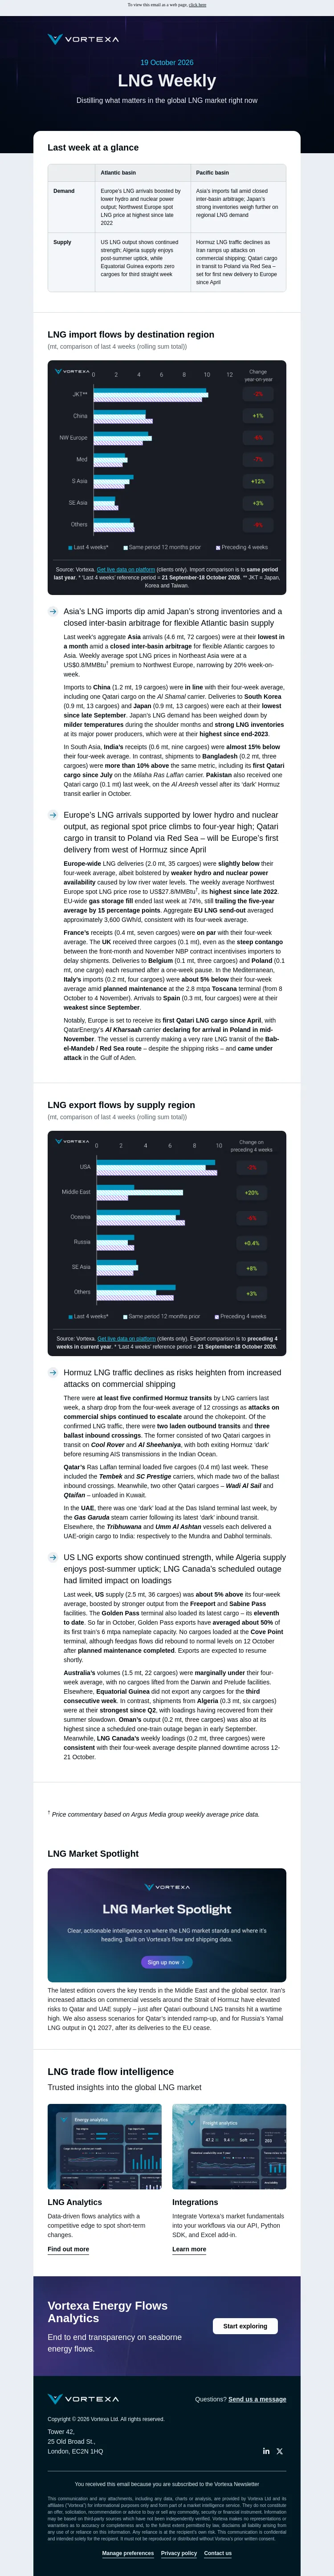
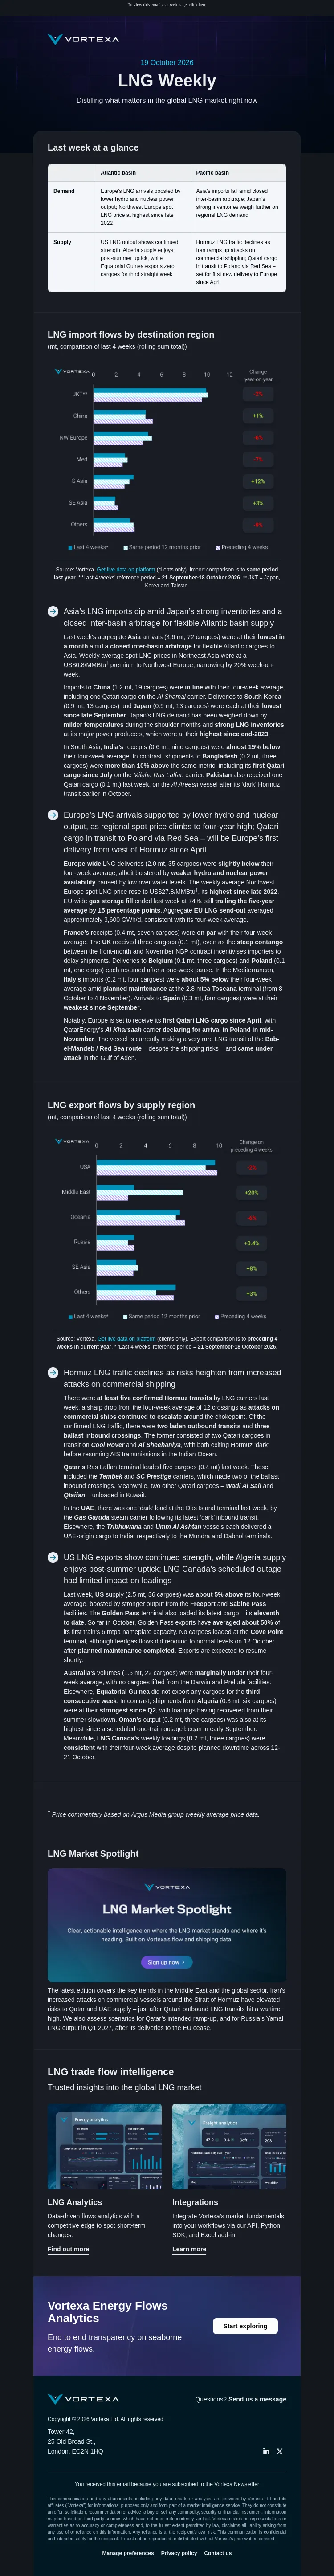
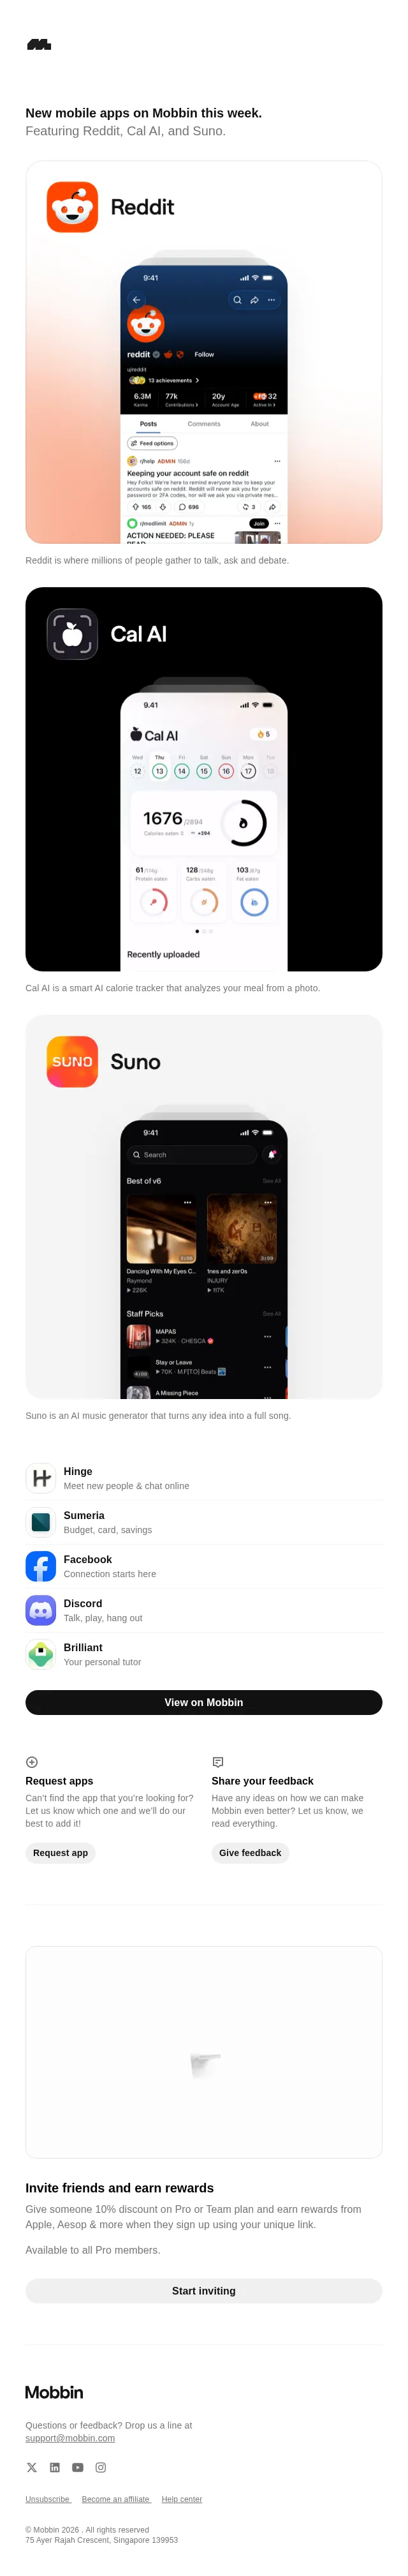
To view this email as a web page, go to the following address: https://marketinfo.vortexa.com/index.php/email/emailWebview?mkt_tok=ODM3LU1aRS01NzgAAAGlF1LoB-w-bFePdYv0cM0o_KKgyVuruVuLVkkzg_KgjfQTJ-OD1CmsSIBBXm-n68R6ATXJSvccjqqTK2kREk8UmiDDG67qqneNVCwomWziIks ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoBz71S5a9L6h8GNJmBtOmbJ79Ho5s7pC98fBWeDALclXzFH9c972SPPGKXyZrOTPQnw0=) 26 October 2026LNG Weekly Distilling what matters in the global LNG market right nowIn partnership with KayrrosLast week at a glanceAtlantic basinPacific basinDemandEurope’s LNG arrivals rise as net gas storage withdrawals begin; inter-basin arbitrage back to marginalAsia’s imports remain stable despite spot LNG prices hitting a new wartime highSupplyUS LNG output climbs to highest since June; Australia exports dampened by Wheatstone’s planned downtimeHormuz LNG traffic momentum slows amid elevated risks of vessel attacks FOCUS TOPICLNG import flows by destination region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoBwIUuAritRnmee2110wCuR4mXeL8lrOFa8tOQuIg4vqGsiky5MOcuR-nFjKgFdeL72Y=) (clients only). Import comparison is to same period last year. * ‘Last 4 weeks’ reference period = 28 September-25 October 2026. ** JKT = Japan, Korea and Taiwan. Asia’s LNG imports steady amid final pre-winter restocking push; regional spot prices hit wartime high as Hormuz transits slow Last week's aggregate Asia arrivals (5.2 mt, 81 cargoes) were marginally above their four-week average as buyers continued to rebuild inventories ahead of winter, even as regional spot prices rose for a third straight week to a wartime high of US$30/MMBtu† (weekly average basis). Deliveries to China (1.5 mt, 23 cargoes) were almost 20% above their four-week average, including three cargoes from Qatar. South Korea’s receipts (0.8 mt, 12 cargoes) were at their lowest since early September, while shipments to Japan (1.1 mt, 16 cargoes) were more than 5% above their recent trendline thanks to warmer-than-expected autumn temperatures. Japan’s wholesale electricity prices have hit their highest since December 2022 but strong LNG inventories held by major power producers will likely limit LNG import upside. In South and Southeast Asia, volumes to India (0.6 mt, eight cargoes) dipped further ahead of upcoming holidays. Pakistan received one Qatari cargo (0.1 mt) for the second consecutive week, while the Philippines imported its first cargo from Qatar since the start of the US-Iran war – on the Seapeak Arwa carrier. Europe’s LNG arrivals grow slightly as gas storage withdrawals begin; inter-basin arbitrage for flexible Atlantic cargoes to Asia back to marginal Europe-wide LNG deliveries (2.1 mt, 36 cargoes) were 5% above their four-week average, amid a marginal inter-basin arbitrage for flexible Atlantic cargoes to Asia. Weekly average spot LNG prices in Northeast Asia were at a US$1.5/MMBtu† premium to Northwest Europe, the widest in a month. EU-wide gas storage fill ended last week at 75%, still trailing the five-year average by 15 percentage points. The bloc had its first net gas storage withdrawal day of the gas year on 20 October, several weeks later than in 2025. Aggregate EU LNG send-out averaged approximately 3,700 GWh/d, about 5% above its four-week trendline. LNG volumes to France (0.4 mt, seven cargoes) and the Netherlands (0.4 mt, six cargoes) were both consistent with their respective four-week averages, while Germany and the UK did not receive any cargoes last week. The NBP gas contract remained at a discount to the TTF, which disincentivised UK imports. In the Mediterranean, Spain’s weekly arrivals (0.5 mt, eight cargoes) were at their highest since March. Shipments to Italy (0.2 mt, three cargoes) were about 5% below their four-week average as adverse weather conditions affected unloading at the Adriatic and Ravenna terminals. In the wider region, Egypt’s receipts (0.1 mt, two cargoes) were at their lowest since June amid seasonally weaker demand, increased piped gas flows from Israel, and gas-to-oil switching for power generation. FOCUS TOPICLNG export flows by supply region (mt, comparison of last 4 weeks (rolling sum total)) Source: Vortexa. Get live data on platform (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoB-af2_TaT-UUb-5h1CSOWgW9dBUtVreCPsVry5EfcOq0vFe1nqjWjTlAqiCM6dauAfs=) (clients only). Export comparison is to preceding 4 weeks in current year. * ‘Last 4 weeks’ reference period = 28 September-25 October 2026. Hormuz LNG traffic dips as elevated risks of vessel attacks continue to dampen transit momentum There were at least six confirmed Hormuz transits by LNG carriers last week – around half of the four-week average, as the threat of vessel attacks weighs on flows through the chokepoint. The confirmed LNG traffic included ‘dark’ laden outbound transits by the SC Prestige (Qatar cargo) and Gas Polaris (UAE cargo) carriers, which subsequently completed ship-to-ship (STS) transfers east of Hormuz, off Oman. Qatar’s Ras Laffan terminal loaded four cargoes (0.3 mt) last week, all of which remained west of Hormuz. These included Kuwait-bound cargoes on the Wadi Al Sail and Umm Al Amad vessels: the former has already discharged, while the latter is currently offloading. Kuwait’s weekly imports (0.1 mt, one cargo) declined to their lowest since May due to softer gas demand during the shoulder season. In the UAE, there was one ‘dark’ load at the Das Island terminal last week, by the Gas Polaris steam carrier. Meanwhile, several other LNG vessels resumed AIS transmissions east of Hormuz, confirming earlier ‘dark’ outbound Hormuz transits or STS activity. Examples include ADNOC’s Mubaraz carrier, which has arrived at India’s Dahej terminal, and QatarEnergy’s Tembek Q-Flex vessel, which is approaching Southeast Asia. US LNG exports climb to highest since June as Cove Point restarts; Wheatstone’s planned outage weighs on Australia output Last week, US supply (2.6 mt, 38 cargoes) was at its highest since June as the Cove Point terminal resumed exports (0.1 mt, two cargoes) for the first time in a month. Shipments from the Cameron facility (0.3 mt, five cargoes) were also at their strongest since August, while Golden Pass loaded one cargo (0.1 mt) for the second consecutive week. Australia’s volumes (1.5 mt, 21 cargoes) were about 5% below their four-week average, owing to the start of scheduled maintenance at the Wheatstone facility, which lifted no cargoes. Elsewhere, Equatorial Guinea did not export any cargoes for the fourth straight week, while Trinidad and Tobago‘s output (0.2 mt, three cargoes) was at its highest since a planned one-train outage at the Atlantic LNG terminal began earlier in October. Meanwhile, shipments from LNG Canada (0.2 mt, three cargoes) were consistent with their four-week average, despite scheduled downtime until 21 October. † Price commentary based on Argus Media group weekly average price data. FOCUS TOPICLNG Market SpotlightFocus topic chart (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoB-GgdGkfSHJ0wqZCvzTKk8_Dnf4p1qfHH4o-hWGUmzTgn-7StX0aIm5i0zuYGZkxszo=) Source: Vortexa, KayrosDaily data from the last 3 months - updated for 26 January 2026 The latest edition covers the key trends in the Middle East and the global sector. Iran’s increased attacks on commercial vessels around the Strait of Hormuz have elevated risks to Qatar and UAE supply – just after Qatari outbound LNG transits hit a wartime high. We also assess scenarios for Qatar’s intended ramp-up, and for Russia’s Yamal LNG output in Q1 2027, after its deliveries to the EU cease.LNG trade flow intelligence Trusted insights into the global LNG marketLNG intelligence dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoBzN_JfbUOexZs1OPDpaRO5_UcT5OJ7ORLHtU5SExyie7f5zPs8GfzIgK0AR7peij12w=) LNG Analytics Data-driven flows analytics with a competitive edge to spot short-term changes. Find out more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoBzN_JfbUOexZs1OPDpaRO5_UcT5OJ7ORLHtU5SExyie7f5zPs8GfzIgK0AR7peij12w=) Outage report dashboard (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoB1IpJ3LMau5R6JuhJI-zOvw74HQaQB3f5yfG1Ke3rmoBm1_nzVvs3ARTOGClnGrs46c=) Integrations Integrate Vortexa’s market fundamentals into your workflows via our API, Python SDK, and Excel add-in. Learn more (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoB1IpJ3LMau5R6JuhJI-zOvw74HQaQB3f5yfG1Ke3rmoBm1_nzVvs3ARTOGClnGrs46c=) Vortexa Energy Flows Analytics End to end transparency on seaborne energy flows.Start exploring (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoB9y9qVH_gN2kLWMotgLOrGpIbagKuDhGQKYC5Mz9pPHBULCZu2N-7Bm91ant_0C6WbQ=) Vortexa (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoBz71S5a9L6h8GNJmBtOmbJ79Ho5s7pC98fBWeDALclXzFH9c972SPPGKXyZrOTPQnw0=) Questions? Send us a message (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoB5YEcYeW2TvaW32uxbceMLo3AYo4KzOs4U0iegNbnbturqIs9XfVvoCmJbirVkurBR8=) Copyright © 2026 Vortexa Ltd. All rights reserved. Tower 42,25 Old Broad St.,London, EC2N 1HQLinkedIn (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoB4xzlJpyqFn56NHAP6kF504ll2CTb1P4sCnDmK9R6MQ2CNnEcMp-WZLYnMwXFxUGvak=) X (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoB7XmZFhexk6kQisIg39KXcVOIYLbcQzwuHMQqYIZ8pV8yQLCMBwZj7ii0U-pMjR8dTM=) You received this email because you are subscribed to the Vortexa Newsletter This communication and any attachments, including any data, charts or analysis, are provided by Vortexa Ltd and its affiliates (“Vortexa”) for informational purposes only and form part of a market intelligence service. They do not constitute an offer, solicitation, recommendation or advice to buy or sell any commodity, security or financial instrument. Information may be based on third-party sources which have not been independently verified. Vortexa makes no representations or warranties as to accuracy or completeness and, to the fullest extent permitted by law, disclaims all liability arising from any use of or reliance on this information. Any reliance is at the recipient’s own risk. This communication is confidential and intended solely for the recipient. It must not be reproduced or distributed without Vortexa’s prior written consent. Manage preferences (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoBhY6Kh_68kmkD60BkzwJJbU-pIYTFu6cKicUWrCBjc3w-FsjuugaVgZTXpEwBsG3teo=) Privacy policy (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoBy8wqXjOJNo8aB6Rc7k9cYynKOYUAU4I0KtLiX3sLExj7mVDKP3CMHCenceNYBIs3PA=) Contact us (https://marketingmail.vortexa.com/ODM3LU1aRS01NzgAAAGlF1LoB5YEcYeW2TvaW32uxbceMLo3AYo4KzOs4U0iegNbnbturqIs9XfVvoCmJbirVkurBR8=) .
- Accession
- nse/vortexa/2026-10-26/5024
- From
- Vortexa · analysts@vortexa.com
- Sent
- 26 October 2026 · 13:00 UTC